

-
September 24, 2026
-
BySiddhi R
Renewal of 12A and 80G Registration: Complete Guide for NGOs
Introduction
For charitable trusts, societies, and non-profit organizations, Renewal of 12A and 80G Registration helps continue applicable tax benefits and donor deduction eligibility. From 1 April 2026, applications relating to regular registration of non-profit organizations and approval for donor deduction benefits are governed by the Income-tax Act, 2025 framework. Eligible organizations need to apply through the prescribed forms based on their existing status, activities, and applicable requirements.
For this blog, we will explain the updated renewal process, eligibility, required documents, validity, timelines, and key compliance points for charitable organizations.
Key Highlights
- From 1 April 2026, applications relating to regular registration and approval are governed by the Income-tax Act, 2025 framework, with applicable forms prescribed for such filings.
- Existing registrations or approvals should generally be renewed by applying at least six months before the expiry date.
- Section 332 registration is generally valid for five tax years, while eligible NPOs meeting the conditions under Section 332(5) may receive validity for ten tax years.
- Approval under Section 354 for donor tax deduction benefits is generally valid for five tax years, making timely Renewal of 12A and 80G Registration important for continued compliance.
- Where registration or approval is granted after processing the application, the Income Tax Department issues the applicable order in Form 107 along with the Unique Registration Number (URN).
What is 12A and 80G Registration?
The terms 12A and 80G registration are still commonly used when referring to the tax benefits available to charitable and non-profit organizations.
- Registration, commonly referred to as 12A/12AB registration under the Income-tax Act, 1961 framework, is now covered under the corresponding provisions of Section 332 of the Income-tax Act, 2025 for eligible non-profit organizations.
- Approval, commonly referred to as 80G approval, is covered under Section 354 of the Income-tax Act, 2025 for enabling eligible donors to claim deductions for qualifying donations.
Organizations must continue meeting the applicable conditions relating to their objects, activities, records, reporting, and other statutory requirements to retain these benefits.
Why is Renewal of 12A and 80G Registration Required?
The Renewal of 12A and 80G Registration helps ensure that tax benefits and donor-related approvals continue to be available to organizations that meet the prescribed legal requirements.
During the regular registration or approval process, the Income Tax Department may examine the organization’s objects, genuineness of activities, supporting documents, and compliance with other laws that are relevant to its stated objectives.
Timely renewal also helps organizations maintain continuity of their tax registration and donor-related approval. For NGOs that depend on donations, maintaining valid approval is particularly important because eligible donors may rely on the organization’s approval status while claiming deductions.
Organizations should therefore monitor their existing registration and approval validity and begin the renewal process within the prescribed time limit.
Renewal Procedure for 12A and 80G Registration
The application should be filed electronically through the Income Tax e-Filing Portal using the applicable form prescribed for the relevant registration or approval category.
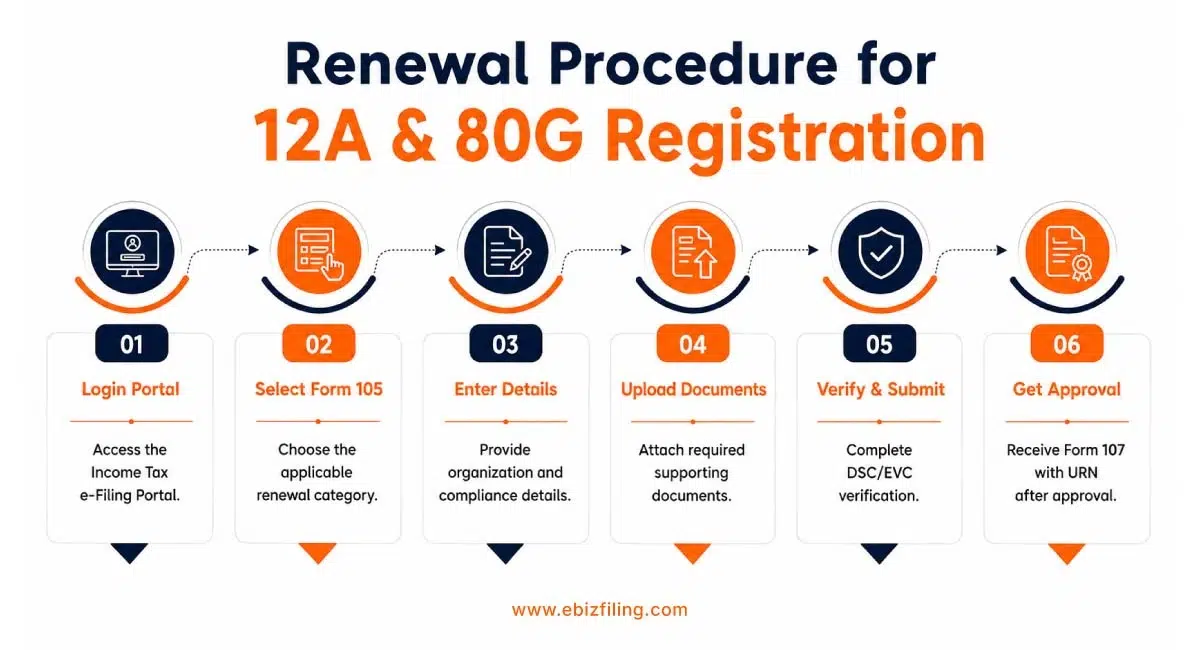
- Log in to the Income Tax e-Filing Portal using the organization’s PAN and password.
- Go to e-File > Income Tax Forms > File Income Tax Forms.
- Select the Forms as per Income Tax Act, 2025 tab and search for Form 105.
- Select the appropriate filing type, tax year, section, and application code.
- Enter the required details about the organization, its registration, office bearers, activities, income, assets, and liabilities, as applicable.
- Upload the supporting documents required for the selected application category.
- Verify and submit Form 105 electronically using a Digital Signature Certificate where mandatory or an Electronic Verification Code in other applicable cases.
- The Principal Commissioner or Commissioner may examine the application and request additional documents or information.
- If registration or approval is granted, the order is issued in Form 107, together with a 16-digit alphanumeric Unique Registration Number or URN.
Documents Required for Renewal of 12A and 80G Registration
The documents required for the Renewal of 12A and 80G Registration depend on the organization’s legal structure, previous registrations, activities, and the application category selected in Form 105.
Commonly required documents may include:
- PAN and basic details of the organization.
- Trust deed, Memorandum of Association, rules, bylaws, or other founding documents.
- Registration certificate issued by the relevant authority.
- Copies of existing 12A, 12AA, 12AB, 80G registrations/approvals or corresponding registration/approval orders under Section 332 or Section 354, as applicable.
- Financial statements for the required preceding years, where applicable.
- Detailed note describing the organization’s activities.
- FCRA registration certificate, where applicable.
- Details of office bearers or persons managing the organization.
- Documents relating to modification of objects, where applicable.
- Details of previous rejection or cancellation of registration or approval, if any.
- Other supporting documents required according to the applicable Form 105 category.
Form 105 specifically requires prescribed documents and information relating to the organization’s establishment, previous registrations, financial information, activities, office bearers, and other applicable matters.
Organizations should ensure that all documents are complete, readable, current, and consistent with the information provided in the application.
Fee Structure of 12A and 80G Registration
The Income Tax Department does not prescribe professional service fees charged by consultants or service providers. The applicable cost depends on the type of application, documentation requirements, professional assistance required, and complexity of the case.
|
Particulars |
Details |
|
Government Filing Fee |
As applicable under the prescribed filing process |
|
Professional Assistance |
Charges may vary depending on documentation, application type, and complexity |
|
Additional Compliance Support |
Additional charges may apply for clarification, corrections, or representation |
|
Complex Applications |
Fees may vary for cases involving modified objects, previous rejection, cancellation, or additional compliance requirements |
Professional service charges should not be presented as government fees because they vary depending on the service provider and the level of assistance required.
Timeline for Renewal of 12A and 80G Registration
The applicable timeline for Renewal of 12A and 80G Registration depends on the type of registration or approval application.
Existing Registration or Approval:
Where an existing regular registration under Section 332 or approval under Section 354 is due to expire, the Renewal of 12A and 80G Registration should generally be filed at least six months before its expiry.
Provisional Registration with Activities Commenced:
Where an organization has provisional registration or approval and has commenced its activities, the regular application is generally required within six months from the commencement of activities.
Activities Not Yet Commenced:
Where activities have not commenced, organizations may need to follow the provisional registration or approval process through the applicable prescribed form instead of Form 105. Form 104 is prescribed for provisional registration or approval, while Form 105 applies to regular registration or approval.
Processing of Regular Applications:
For regular registration or approval cases, the prescribed period for passing the order is generally six months from the end of the quarter in which the application is made.
Therefore, organizations planning the Renewal of 12A and 80G Registration should avoid waiting until the registration is close to expiry and prepare their documents well before the applicable deadline.
Ebizfiling Support for 12A and 80G Renewal
Ebizfiling assists charitable trusts, societies, Section 8 companies, and other eligible non-profit organizations with the Renewal of 12A and 80G Registration. Our team helps review existing registrations, prepare required documents, and support the filing process under the applicable Income Tax provisions.
- Registration Review: We check your existing 12A, 12AB, 80G, or related registration details and validity.
- Document Check: Our team reviews the required organizational, financial, and activity-related documents before filing.
- Form Assistance: We assist with preparing the applicable Form 105 details for registration or approval.
- Filing Support: Ebizfiling supports the online application process and helps reduce common filing errors.
- Query Assistance: If the department requests additional information or clarification, our team can assist with preparing an appropriate response.
Need assistance with Renewal of 12A and 80G Registration? Connect with Ebizfiling experts for document review, application support, and compliance guidance.
Conclusion
Renewal of 12A and 80G Registration helps charitable and non-profit organizations continue their eligibility for applicable tax benefits and donor-related deductions while complying with the updated Income Tax framework. Organizations should review their registration status, validity period, and applicable filing requirements before starting the renewal process. From 1 April 2026, organizations should follow the applicable Income-tax Act, 2025 framework and use the prescribed forms for their registration or approval category. Organizations should select the appropriate application category depending on whether they require registration, approval, or both.
Organizations should also check the validity mentioned in their registration or approval and file within the applicable deadline instead of assuming that every registration has the same five-year validity. Proper documentation, timely filing, and accurate application details can help reduce compliance issues during the renewal process.
Suggested Reads:
Difference between 12A and 80G
How to Download 12A and 80G Certificate?
Form 10B and Form 10BB Audit Requirements
Frequently Asked Questions
1. Can 12A registration renewal and 80G registration renewal have different expiry dates?
Yes. The two approvals may have different validity periods. Eligible organizations satisfying the conditions under Section 332(5) may receive registration for ten tax years, while other cases generally have five-tax-year validity. Organizations should check both approval orders separately instead of assuming the expiry dates are identical.
2. What should an NGO do if it discovers a mistake after filing Form 105?
If an error is noticed after a Form 105 renewal application is submitted, the organization should review the available correction or withdrawal options immediately. During the Renewal of 12A and 80G Registration, checking all information carefully before submission can help avoid such issues.
3. Which NGOs can receive a 10-year 12A registration validity?
An eligible NPO may receive a ten-year 12A registration validity where its total income, calculated without giving effect to the relevant NPO exemption provisions, does not exceed ₹5 crore in each of the two tax years preceding the year in which the application is made. Otherwise, the regular registration period is generally five tax years.
4. Does a 10-year Section 332 registration also extend 80G registration validity to 10 years?
No. The extended ten-year period under Section 332 does not automatically extend the 80G registration validity. Regular approval under Section 354 is generally granted for five tax years, even where the organization qualifies for ten-year registration under Section 332.
5. Can an NGO apply for Section 332 registration and Section 354 approval together?
Yes. Depending on eligibility and existing approval status, an organization may apply for registration under Section 332, approval under Section 354, or both through Form 105. This makes it important to identify the correct application category before starting the Renewal of 12A and 80G Registration.
6. What happens if an NGO misses the prescribed renewal deadline?
If an NGO misses the prescribed renewal timeline, it should review the applicable provisions and available options based on the circumstances. Therefore, organizations planning the Renewal of 12A and 80G Registration should track expiry dates and begin document preparation well in advance.
7. Does changing the objects of a trust affect charitable trust registration renewal?
Yes, it can. If a registered NPO changes its objects in a manner that does not conform to the conditions of registration, additional compliance may be required. Organizations should review amendments made to the trust deed, MOA, or other governing documents before filing.
8. What is the deadline if an NGO starts activities during provisional registration?
Where provisional registration has already been granted and the organization’s activities commence, the regular registration application is generally required within six months from the commencement of activities. This differs from the timeline applicable to certain existing registrations approaching expiry.
9. Can Ebizfiling help check whether my organization needs 12A registration renewal or 80G approval renewal first?
Yes. Ebizfiling can review existing 12A, 12AB, 80G, Section 332, or Section 354 records, validity dates, and applicable filing requirements. This helps determine whether the Renewal of 12A and 80G Registration needs to be handled together or whether one approval requires earlier attention.
10. Can Ebizfiling assist if the Income Tax Department asks for clarification after filing?
Yes. Ebizfiling can assist with document review, Form 105 preparation, filing support, and responses to additional information or clarification requests. This support can be useful during the Renewal of 12A and 80G Registration, especially where previous registrations, modified objects, financial records, or supporting documents require careful review.



80G Registration
Register 80G of income tax in simple steps with Ebizfiling
About Ebizfiling -


September 25, 2026 By Srishti M
OPC Compliance Calendar October 2026: Important Filings & Requirements Introduction The OPC Compliance Calendar October 2026 highlights the key statutory obligations that One Person Companies should monitor during the month. October primarily includes compliance requirements related to financial statement filing […]
September 25, 2026 By Srishti M
PF and ESI Compliance Calendar October 2026: Key Due Dates Introduction The PF and ESI Compliance Calendar October 2026 provides employers with important labour law compliance requirements related to EPF contribution payment and ESI contribution payment for September 2026. […]
September 24, 2026 By Srishti M
Income Tax Compliance Calendar October 2026: Filing Guide Introduction The Income Tax Compliance Calendar October 2026 highlights important income tax obligations applicable to taxpayers, businesses and entities covered under audit and transfer pricing provisions. October 2026 includes key compliance […]