

-
September 12, 2026
-
BySteffy A
Section 196 and 198 of the Income Tax Act 2025: STCG and LTCG
Introduction
Sections 196 and 198 of the Income-tax Act, 2025 prescribe special tax rates for eligible short-term and long-term capital gains arising from specified equity-related assets. Section 196 applies to eligible short-term capital gains, while Section 198 applies to eligible long-term capital gains. These provisions correspond to Sections 111A and 112A of the Income-tax Act, 1961 and apply from 1 April 2026.
This blog explains Section 196 and 198, their applicability, tax rates, conditions, and key differences.
What is Section 196 of the Income Tax Act, 2025?
Section 196 of the Income Tax Act, 2025 provides for the taxation of short-term capital gains arising from the transfer of specified equity-related capital assets. It applies to gains earned from the sale of equity shares, units of an equity-oriented fund, or units of a business trust, subject to prescribed conditions.
Applicability of Section 196
Section 196 applies where:
- The capital gain arises from the transfer of a short-term capital asset.
- The asset is an equity share in a company, a unit of an equity-oriented fund, or a unit of a business trust.
- The sale transaction is chargeable to Securities Transaction Tax (STT) under Chapter VII of the Finance (No. 2) Act, 2004.
Tax Rate under Section 196
Where the conditions of Section 196 are satisfied:
- Short-term capital gains are taxed at 20%.
- The balance of the total income is taxed according to the applicable income tax slab rates.
Benefit of Basic Exemption Limit
Resident individuals and Hindu Undivided Families (HUFs) can claim the benefit of the basic exemption limit. If the total income, excluding short-term capital gains under Section 196, is below the maximum amount not chargeable to tax, the unutilized exemption limit can be adjusted against such gains. Tax at 20% is payable only on the remaining balance.
Exception for IFSC Transactions
The requirement of paying STT does not apply to transactions undertaken on a recognised stock exchange located in an International Financial Services Centre (IFSC), provided the consideration for the transaction is paid or payable in foreign currency.
Deduction under Chapter VIII
If the gross total income includes short-term capital gains taxable under Section 196, deductions under Chapter VIII are allowed only on the gross total income after reducing such short-term capital gains.
To understand how gains from listed shares are classified and taxed, read our guide on income tax rules for equity share trading.
What is Section 198 of the Income Tax Act, 2025?
Section 198 of the Income Tax Act, 2025 provides for the taxation of long-term capital gains arising from the transfer of specified equity-related assets. It applies to long-term gains from equity shares, units of equity-oriented funds, and units of business trusts, subject to the prescribed Securities Transaction Tax conditions.
Applicability of Section 198
Section 198 applies where:
- The total income includes income chargeable under the head “Capital gains.”
- The gain arises from the transfer of a long-term capital asset.
- The asset is an equity share in a company, a unit of an equity-oriented fund, or a unit of a business trust.
- In the case of equity shares, STT has been paid on both acquisition and transfer.
- In the case of units of an equity-oriented fund or business trust, STT has been paid on transfer.
Tax Rate under Section 198
Long-term capital gains exceeding Rs. 1,25,000 are taxable at 12.5%. The balance income, after reducing such long-term capital gains, is taxed according to the applicable income tax rates.
Benefit of Basic Exemption Limit
A resident individual or Hindu Undivided Family can adjust the unused basic exemption limit against long-term capital gains under Section 198. Tax at 12.5% is charged only on the remaining taxable gain after such adjustment.
IFSC Exception
The STT condition does not apply to transfers carried out on a recognised stock exchange located in an International Financial Services Centre, where the consideration is received or receivable in foreign currency.
Deduction under Chapter VIII
Where the gross total income includes long-term capital gains covered under Section 198, deductions under Chapter VIII are allowed only from the gross total income remaining after reducing such capital gains.
Rebate under Section 156
The rebate under Section 156 is allowed from the income tax payable on total income after excluding the tax payable on long-term capital gains covered under Section 198. Therefore, the rebate cannot be used to reduce the tax directly payable on such long-term capital gains.
Meaning of Equity-Oriented Fund
For Section 198, an equity-oriented fund includes a specified mutual fund scheme or an eligible unit-linked insurance scheme meeting the prescribed investment conditions.
- In a fund-of-funds structure, at least 90% of the fund’s proceeds must be invested in another exchange-traded fund, and that fund must invest at least 90% of its proceeds in listed equity shares of domestic companies.
- In other cases, at least 65% of the fund’s total proceeds must be invested in listed equity shares of domestic companies.
The prescribed percentage is calculated with reference to the annual average of the monthly opening and closing figures. For eligible unit-linked insurance schemes, the applicable 90% or 65% condition must be satisfied throughout the policy term.
Taxpayers selling other eligible capital assets may also explore the available capital gains tax exemptions, subject to the conditions prescribed under the Income Tax Act.
Tax Planning Considerations Before Selling Equity Investments
Although Sections 196 and 198 prescribe the tax rates for eligible short-term and long-term capital gains, taxpayers should also consider certain factors before selling equity-related investments. Proper planning helps in calculating the correct tax liability and avoiding common reporting errors.
1. Check the ₹1.25 Lakh LTCG Threshold Before Selling
Under Section 198 of the Income Tax Act, 2025, long-term capital gains from specified equity-related assets exceeding ₹1,25,000 are taxable at the applicable rate, subject to prescribed conditions.
Before selling investments, taxpayers should review their total eligible equity-related LTCG for the financial year. The threshold applies to specified equity-related LTCG and should not be considered applicable to all types of long-term capital gains, such as gains from property, gold, or other assets.
2. Verify the Holding Period of Each Share Purchase Lot
Investors often purchase shares of the same company on different dates. In such cases, each purchase lot may have a different tax treatment depending on its holding period.
Before selling shares, taxpayers should review the purchase date of each lot to determine whether the resulting gain qualifies as short-term capital gain under Section 196 or long-term capital gain under Section 198.
A stock held in the portfolio for several years does not automatically mean that all shares qualify as long-term if additional shares were purchased later.
3. Review Available Capital Losses Before Booking Gains
Before selling investments that have generated profits, taxpayers should review available capital losses, including current year losses and eligible brought-forward losses.
Short-term capital losses can generally be adjusted against short-term and long-term capital gains, while long-term capital losses can generally be adjusted against long-term capital gains, subject to the applicable provisions of the Income Tax Act, 2025.
Reviewing available losses before selling securities can help in better tax planning.
4. Check Grandfathering Rules for Shares Acquired Before 31 January 2018
Investors holding eligible equity shares acquired before 31 January 2018 should consider the grandfathering provisions while calculating long-term capital gains.
For such shares, the cost of acquisition is determined according to prescribed rules considering factors such as the fair market value as on 31 January 2018. Using only the original purchase price may result in an incorrect calculation of taxable gains.
5. Verify Cost and Holding Period Rules for Bonus Shares
Bonus shares require careful consideration while calculating capital gains because their cost of acquisition is determined according to specific tax rules.
Before selling bonus shares, taxpayers should verify:
- Date of allotment of bonus shares
- Applicable cost of acquisition rules
- Holding period calculation
Correctly identifying these details helps in determining whether the resulting gain is taxable as short-term or long-term capital gain.
6. Review Buyback Transactions Separately Before Accepting an Offer
Share buyback transactions may have different tax implications compared to normal sale of equity shares through a stock exchange.
Before accepting a buyback offer, investors should review the applicable provisions of the Income Tax Act, 2025 and understand the tax treatment and reporting requirements applicable to the transaction.
Difference Between Section 196 and 198 of Income Tax Act
|
Particulars |
Section 196 |
Section 198 |
|
Applicable Capital Gain |
Short-Term Capital Gains (STCG) |
Long-Term Capital Gains (LTCG) |
|
Earlier Provision |
Section 111A of the Income-tax Act, 1961 |
Section 112A of the Income-tax Act, 1961 |
|
Applicable Assets |
Equity shares, equity-oriented mutual funds, and business trust units |
Equity shares, equity-oriented mutual funds, and business trust units |
|
Holding Period |
Short-term capital assets |
Long-term capital assets |
|
Tax Rate |
20% |
12.5% |
|
Exemption Threshold |
No exemption threshold |
Tax applies only on LTCG exceeding Rs. 1,25,000 |
|
Securities Transaction Tax (STT) |
STT must be paid on the sale transaction |
STT must be paid on acquisition and transfer of equity shares, and on transfer of equity-oriented fund units or business trust units |
|
Basic Exemption Limit Benefit |
Available to resident individuals and HUFs |
Available to resident individuals and HUFs |
|
IFSC Relaxation |
STT condition does not apply to eligible IFSC transactions in foreign currency |
STT condition does not apply to eligible IFSC transactions in foreign currency |
|
Chapter VIII Deduction |
Deduction is allowed after reducing STCG from Gross Total Income |
Deduction is allowed after reducing LTCG from Gross Total Income |
|
Rebate under Section 156 |
Section 196 does not contain a separate rebate restriction. Eligibility must be checked under Section 156 and the applicable tax regime |
The rebate under Section 156 cannot reduce the tax payable on long-term capital gains covered under Section 198.le on |
Conditions for Applicability of Sections 196 and 198 of Income Tax Act
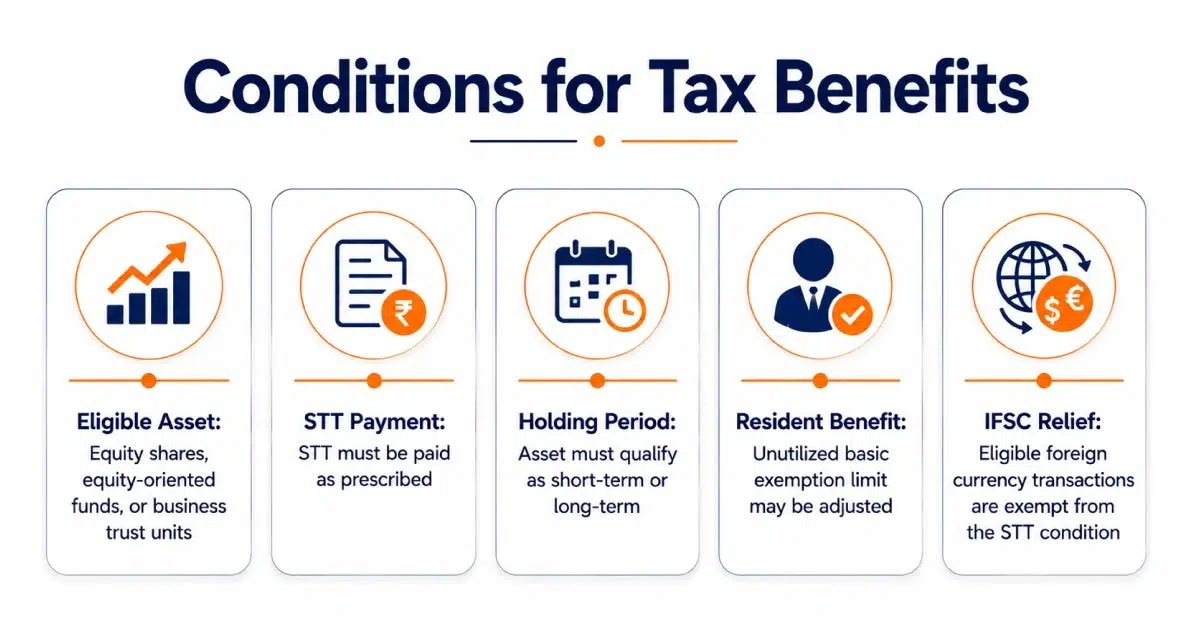
- Eligible Capital Asset: The gain must arise from an eligible equity share, equity-oriented fund, or business trust unit.
- Securities Transaction Tax (STT): STT must be paid as prescribed under the applicable section.
- Holding Period: The asset must qualify as a short-term or long-term capital asset based on the prescribed holding period.
- Resident Benefit: Resident individuals and HUFs can adjust the unutilized basic exemption limit against eligible capital gains.
- IFSC Relaxation: Eligible transactions carried out through recognized stock exchanges in an IFSC in foreign currency are exempt from the STT condition.
Capital gains arising from residential property may be governed by different exemption provisions, including Section 82 of the Income Tax Act, 2025.
Section 87A Warning: Do Not Assume Rebate Applies to Equity Capital Gains
Many taxpayers assume that being eligible for the Section 87A rebate automatically eliminates their tax liability. However, special-rate income such as eligible equity-related capital gains requires separate evaluation. A resident individual may still have tax liability on specified short-term or long-term capital gains even if the total income falls within the rebate limit, depending on the applicable provisions and nature of income.
Case Study: How FIFO Can Create Different Tax Treatment in One Share Sale
Assume an investor purchases shares of the same company in multiple transactions:
|
Purchase Date |
Number of Shares |
Purchase Price |
|
January 2025 |
100 shares | ₹500 per share |
| October 2025 | 100 shares |
₹800 per share |
|
June 2026 |
100 shares |
₹900 per share |
The investor sells 150 shares in August 2026 at ₹1,000 per share.
Since shares purchased earlier are considered first under the FIFO (First-In First-Out) method, the sale will first include:
- 100 shares purchased in January 2025
- 50 shares purchased in October 2025
Therefore, the same sale transaction may include different tax treatments:
- Older shares may qualify as long-term capital gains
- Recently purchased shares may qualify as short-term capital gains
This means a single sell order can result in capital gains taxable under different provisions depending on the purchase lots involved.
Mistakes While Selling Equity Investments
Investors often make the following mistakes while calculating capital gains:
- Applying one holding period to the entire shareholding instead of checking individual purchase lots.
- Ignoring FIFO while determining which shares are considered sold.
- Assuming the ₹1.25 lakh LTCG threshold applies to all types of capital gains.
- Not reviewing grandfathering provisions for eligible shares acquired before 31 January 2018.
- Using average purchase cost for bonus shares instead of applying applicable tax rules.
- Assuming Section 87A rebate automatically reduces tax on special-rate equity capital gains.
- Applying outdated buyback tax rules while reporting share-related transactions.
Checklist Before Selling Equity Shares
Before selling equity investments, taxpayers should review the following points to calculate the correct capital gains and understand the applicable tax impact:
- Verify purchase dates and lot-wise holding periods to determine whether the gains qualify as STCG or LTCG.
- Check FIFO applicability for shares purchased through multiple transactions before finalising the sale.
- Calculate eligible equity-related LTCG and review the available ₹1.25 lakh threshold under applicable provisions.
- Review current year and brought-forward capital losses to understand possible adjustments against eligible capital gains.
- Check grandfathering provisions for eligible equity shares acquired before 31 January 2018.
- Verify the cost of acquisition and holding period for bonus shares, rights issues, or other corporate action-related holdings.
- Review the applicability of Section 87A rebate before assuming that it will reduce tax liability on special-rate equity capital gains.
- Evaluate buyback transactions separately and check the applicable tax treatment before accepting any buyback offer.
- Maintain purchase statements, demat records, and transaction details for accurate capital gain calculation and Income Tax Return reporting.
Get Help with Capital Gains Tax Filing
Ebizfiling can help you calculate short-term and long-term capital gains under Section 196 and 198, file your Income Tax Return, respond to tax notices, and meet the applicable reporting requirements.
Related Services:
- Income Tax Return Filing
- Income Tax Notice Response
- Tax Planning and Advisory
- NRI Income Tax Return Filing
Get professional help with capital gains tax calculation and Income Tax Return filing under Section 196 and 198.
Conclusion
Section 196 and 198 of the Income Tax Act, 2025 set out separate tax rules for short-term and long-term capital gains on equity shares, equity-oriented funds, and business trust units. Section 196 taxes eligible short-term gains at 20%, while Section 198 taxes long-term gains above Rs. 1,25,000 at 12.5%. These sections replace Section 111A and 112A of the Income-tax Act, 1961.
Since the tax treatment depends on the type of asset, holding period, STT payment, and applicable exemptions, taxpayers should review these conditions carefully before filing their Income Tax Return.
Suggested Reads:
Capital Gains on Crypto Transactions in India 2026
FAQs on Section 196 and 198 of Income Tax Act
1. Can shares purchased at different times have different tax treatment in the same sale transaction?
Yes. When shares of the same company are purchased on different dates, each purchase lot may have a different holding period. The tax treatment depends on whether the relevant lot qualifies as short-term or long-term capital gain. FIFO principles help determine which shares are considered sold from demat holdings while calculating capital gains.
2. How is the cost of acquisition calculated for eligible listed equity shares acquired before 31 January 2018?
January 2018, grandfathering provisions apply while determining the cost of acquisition for calculating long-term capital gains. The cost is calculated according to prescribed rules considering factors such as the prescribed fair market value as on 31 January 2018 and the actual acquisition cost.
3. How are bonus shares taxed when they are sold?
Bonus shares have specific rules for determining their cost of acquisition and holding period while calculating capital gains. Since bonus shares are allotted without direct purchase consideration, taxpayers should verify the applicable tax rules before selling them to determine the correct taxable gains.
4. Can Section 87A rebate be claimed against tax payable on equity share capital gains?
The applicability of Section 87A rebate depends on the nature of income, applicable provisions, and the relevant assessment year. Taxpayers should separately evaluate whether the rebate applies to special-rate equity capital gains before calculating their final tax liability.
5. Is STT mandatory under Section 196 and 198?
Yes, STT is generally required under Section 196 and 198. However, eligible transactions carried out through a recognised stock exchange in an IFSC and settled in foreign currency are exempt from this condition.
6. Can the basic exemption limit be adjusted against gains under Section 196 and 198?
Yes. A resident individual or HUF can adjust the unused basic exemption limit against eligible gains under Section 196 and 198, subject to the conditions provided in the Act.
7. How does Section 196 and 198 treat STT on equity shares?
Under Section 196, STT must be chargeable on the sale transaction. Under Section 198, STT is generally required on both acquisition and transfer of equity shares.
8. Are Chapter VIII deductions allowed against STCG under Section 196?
No direct deduction is allowed from STCG under Section 196. Chapter VIII deductions are allowed only from the gross total income remaining after reducing such short-term capital gains.
9. How should capital gains under Section 196 and 198 be reported in the Income Tax Return?
Capital gains under Section 196 and 198 must be reported in the applicable capital gains schedule of the Income Tax Return. Ebizfiling can assist with gain calculation, tax treatment, and accurate ITR filing.
10. Can Ebizfiling help with LTCG under Section 198 and tax notice response?
Yes. Ebizfiling can help calculate LTCG under Section 198, prepare the relevant ITR, review STT and exemption conditions, and assist with income tax notice responses.



Reliable Income Tax Filing Services
Get complete Income Tax Return support to ensure timely filing and smooth tax compliance every year.
About Ebizfiling -


September 21, 2026 By Srishti M
Raw Sugar Import Under TRQ: DGFT Eases Processing & Sale Deadline Introduction India has introduced an important change to the raw sugar import framework under the Tariff Rate Quota (TRQ) scheme. On 20 August 2026, the Directorate General of Foreign […]
September 21, 2026 By Srishti M
UPI MDR Charges 2026: 0.4% MDR on Payments Above ₹2,000 Introduction UPI MDR Charges 2026 introduce an important change for selected merchant payments made through the Unified Payments Interface. From 15 October 2026, a Merchant Discount Rate (MDR) of 0.4% […]
September 21, 2026 By Srishti M
EPFO Employees’ Enrollment Campaign 2026: Guide Overview The EPFO Employees’ Enrollment Campaign 2026 is a special, time-bound opportunity for employers to bring eligible employees under EPF coverage where they were left out during the prescribed historical period. Officially known as […]