

-
September 17, 2026
-
BySteffy A
Section 111A and 112A of the Income Tax Act: STCG and LTCG Tax Rules
Introduction
Section 111A and Section 112A of the Income-tax Act, 1961 governed the taxation of eligible short-term and long-term capital gains arising from equity shares, equity-oriented mutual funds, and units of business trusts. Section 111A applied to eligible short-term capital gains, while Section 112A applied to eligible long-term capital gains.
From 1 April 2026, the corresponding provisions are contained in Section 196 and Section 198 of the Income-tax Act, 2025. Sections 111A and 112A remain relevant for transactions, returns, assessments, and other matters governed by the Income-tax Act, 1961.
This article explains the earlier provisions under Sections 111A and 112A and their corresponding treatment under Sections 196 and 198 of the Income-tax Act, 2025.
What is Section 111A of the Income Tax Act?
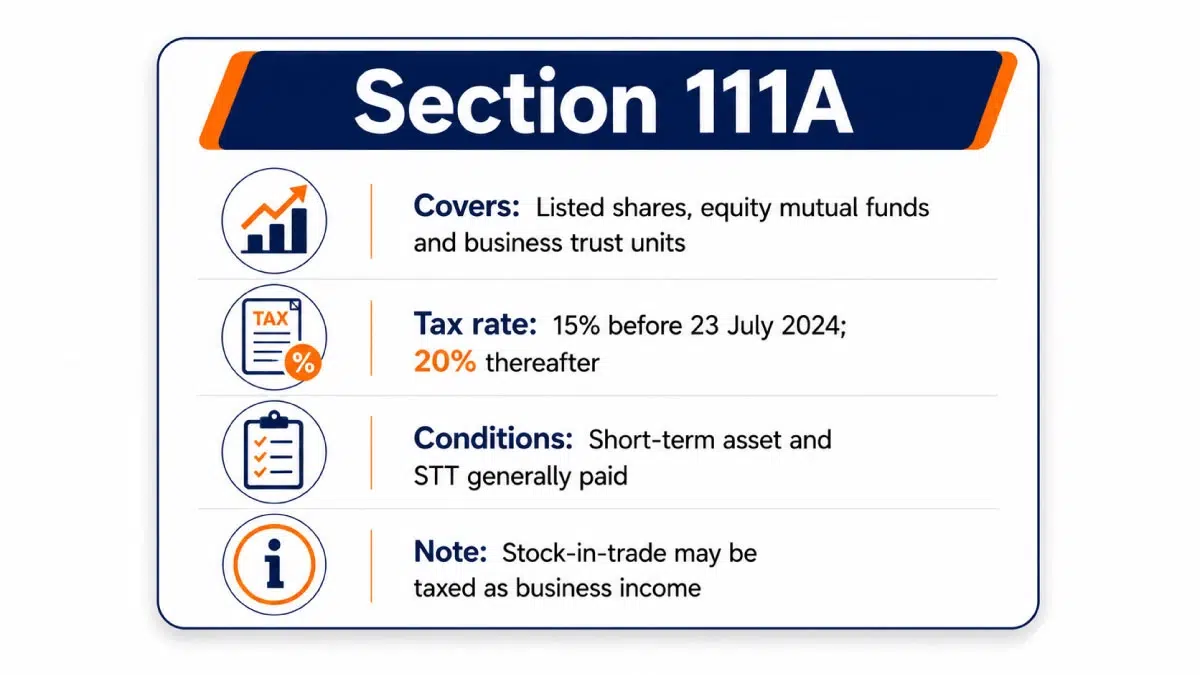
Section 111A of the Income Tax Act provides a concessional tax rate on eligible short-term capital gains arising from the transfer of specified equity securities. It generally covers listed equity shares, units of an equity-oriented mutual fund, and units of a business trust where the prescribed STT conditions are satisfied.
For eligible transfers made on or after 23 July 2024, short-term capital gains under Section 111A are generally taxable at 20%. The earlier rate of 15% generally applied where the transfer took place before 23 July 2024. Applicable surcharge and health and education cess are charged separately.
The security must generally be held as a capital asset. If shares or securities are held as stock-in-trade, the resulting income may be treated as business income instead of capital gains.
Assets Covered under Section 111A
Section 111A generally applies to short-term capital gains arising from the transfer of:
- Listed equity shares in a company
- Units of an equity-oriented mutual fund
- Units of a business trust
- The prescribed holding period and STT conditions must also be satisfied.
Section 111A Tax Rate
|
Date of transfer |
Tax rate |
|
Before 23 July 2024 |
15% |
| On or after 23 July 2024 |
20% |
Note: For gains governed by the Income-tax Act, 2025 from 1 April 2026, refer to the corresponding provisions of Section 196.
Conditions for Taxation under Section 111A
To claim taxation under Section 111A, the following conditions must generally be satisfied:
- The gain must arise from the transfer of an eligible equity share, equity-oriented mutual-fund unit, or business-trust unit.
- Also, the asset must qualify as a short-term capital asset.
- The security should be held as a capital asset and not as a stock-in-trade.
- STT should generally have been paid on the transfer.
- The transaction must satisfy the other prescribed conditions under the Income-tax Act.
Certin transactions undertaken on a recognised stock exchange located in an International Financial Services Centre may receive specified treatment even where STT is not paid, subject to the prescribed conditions.
Section 87A Rebate and Special Rate Capital Gains
Taxpayers should evaluate the applicability of Section 87A rebate separately while calculating tax liability on equity share gains.
The rebate under Section 87A is subject to applicable conditions, tax regime, tax year, and statutory provisions. Investors should not assume that having income below the rebate threshold will automatically eliminate tax payable on special-rate capital gains such as eligible equity STCG or LTCG.
Before selling shares, investors should review:
- Total taxable income after considering capital gains
- Applicable tax regime
- Nature of capital gains (STCG or LTCG)
- Whether the income is taxable at special rates
Proper tax planning helps investors avoid incorrect assumptions regarding rebate availability while calculating their final tax liability.
What is Section 112A of the Income Tax Act?
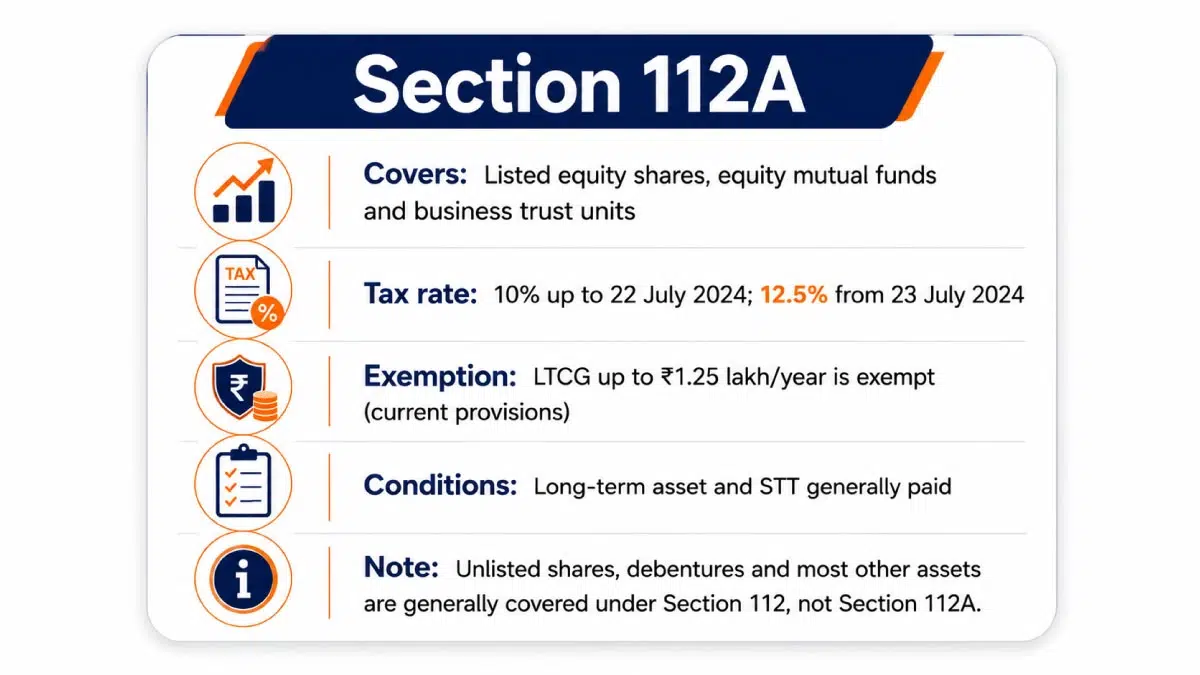
Section 112A provides a concessional tax rate on eligible long-term capital gains arising from specified equity-related assets. It generally applies to listed equity shares, units of an equity-oriented mutual fund, and units of a business trust where the prescribed STT conditions are satisfied.
For eligible transfers made on or after 23 July 2024, aggregate long-term capital gains exceeding ₹1.25 lakh during the financial year are generally taxable at 12.5%. For transfers made before 23 July 2024, the applicable rate was generally 10%. However, for FY 2024-25, the amended aggregate annual threshold of ₹1.25 lakh applies to total gains covered under Section 112A, including transfers made before and after.
Section 112A applies only to specified equity-related assets. Unlisted shares, debentures, and other capital assets are generally governed by Section 112 or another applicable provision.
How Is Section 112 Different from Section 112A?
Section 112 generally covers long-term capital gains arising from assets that are not specifically covered under Section 112A, such as certain unlisted shares, immovable property, debentures, and other capital assets. Section 112A specifically covers eligible long-term capital gains from listed equity shares, equity-oriented mutual funds, and units of business trusts where the prescribed STT conditions are satisfied.
Assets Covered under Section 112A
Section 112A generally covers long-term capital gains arising from:
- Listed equity shares in a company
- Units of an equity-oriented mutual fund
- Units of a business trust
The Income Tax Department’s Schedule 112A reporting guidance also identifies these assets for reporting long-term capital gains where STT has been paid.
You can also read our guide on Income Tax Rules for Equity Share Trading to understand how investment, delivery-based trading, and business income from shares may be taxed.
Section 112A Tax Rate and Aggregate Threshold
|
Applicable period |
Tax rate |
Aggregate annual threshold |
|
Financial years before FY 2024-25 |
10% | ₹1 lakh |
| FY 2024-25: transfers before 23 July 2024 | 10% |
₹1.25 lakh for aggregate Section 112A gains |
|
FY 2024-25: transfers on or after 23 July 2024 |
12.5% | ₹1.25 lakh for aggregate Section 112A gains |
| FY 2025-26 under the Income-tax Act, 1961 | 12.5% |
₹1.25 lakh |
|
Tax Year 2026-27 onward under Section 198 |
12.5% |
₹1.25 lakh |
The ₹1.25 lakh exemption is an aggregate annual threshold and not a separate exemption for every transaction.
Applicable surcharge and health and education cess are charged separately.
Conditions for Taxation under Section 112A
The following conditions generally apply:
- The asset must be a listed equity share, equity-oriented mutual-fund unit, or business-trust unit.
- The asset must qualify as a long-term capital asset.
- STT should generally be paid on the transfer.
- In the case of equity shares, STT should generally have been paid on acquisition and transfer, subject to notified exceptions.
- The capital gain must be reported in the applicable ITR schedules.
- Chapter VI-A deductions cannot generally be claimed directly against income taxable at the special rate under Section 112A.
The availability of a rebate under Section 87A against tax payable on Section 112A gains depends on the relevant tax year, tax regime, and applicable statutory position.
Holding Period for Section 111A and 112A
Listed equity shares, equity-oriented mutual-fund units, and specified listed business-trust units are generally treated as short-term capital assets when held for 12 months or less.
They are generally treated as long-term capital assets when held for more than 12 months.
The applicable holding period should be checked according to the asset type and relevant legal provisions.
Tax Planning Strategy 1: Check FIFO Before Selling Shares
When an investor purchases shares of the same company multiple times, each purchase lot may have a different acquisition date and tax treatment. The holding period should be checked separately for each lot instead of considering the entire portfolio holding period.
For shares held in demat form, the FIFO (First-In-First-Out) method is generally used to determine which shares are considered sold first. This means the shares purchased earlier are treated as sold before the shares purchased later.
Therefore, a single sell transaction may include both short-term and long-term capital gains if different purchase lots fall under different holding periods.
Before selling shares, investors should review:
- Purchase dates of each lot
- Quantity available in each lot
- Applicable STCG or LTCG classification
- Cost of acquisition details
Proper lot-wise analysis helps avoid incorrect calculation of capital gains.
Tax Planning Strategy 2: Review Capital Losses Before Selling Shares
Before selling shares that have generated gains, investors should review their available capital losses. Proper utilisation of eligible losses can help in planning the timing of share sales.
Under capital gains provisions:
- Short-term capital loss can generally be adjusted against short-term capital gains as well as long-term capital gains.
- Long-term capital loss can generally be adjusted only against long-term capital gains.
- Investors should also consider eligible brought-forward capital losses while planning share transactions.
However, loss adjustment is subject to applicable Income-tax provisions and reporting requirements. Investors should maintain proper records of previous transactions and capital loss details before claiming set-off.
Tax Planning Strategy 3: Check Grandfathering Rules for Shares Acquired Before 31 January 2018
Investors holding eligible listed equity shares acquired before 31 January 2018 should consider the grandfathering provisions while calculating long-term capital gains.
For such shares, the cost of acquisition is determined using the prescribed calculation mechanism, which considers factors such as:
- Actual cost of acquisition
- Fair market value as on 31 January 2018
- Sale consideration
Using only the original purchase cost may result in incorrect LTCG calculation for eligible old holdings.
Investors should maintain historical purchase records and verify the applicable cost calculation method before selling such shares.
Tax-planning strategy 4: Check 31 January 2018 Grandfathering for Very Old Listed Equity
Investors holding eligible listed equity shares acquired before 31 January 2018 should consider the grandfathering provisions while calculating long-term capital gains.
For such shares, the cost of acquisition is determined using the prescribed calculation mechanism, which considers factors such as:
- Actual cost of acquisition
- Fair market value as on 31 January 2018
- Sale consideration
The grandfathering rule protects eligible gains accrued up to 31 January 2018 by allowing a higher cost of acquisition to be considered, subject to the prescribed calculation method.
Using only the original purchase cost may result in incorrect LTCG calculation for eligible old holdings. Investors should maintain historical purchase records and verify the applicable cost calculation before selling such shares.
Tax Planning Strategy 5: Consider Tax Impact of Bonus Shares Before Selling
Bonus shares may require separate tax consideration because their cost of acquisition is determined differently from regularly purchased shares.
For bonus shares issued on or after 1 April 2001, the cost of acquisition is generally considered nil for capital gains calculation purposes, subject to applicable provisions. Therefore, when such bonus shares are sold, the entire sale consideration may result in taxable capital gains after considering the applicable holding period.
Before selling bonus shares, investors should review:
- Date of bonus share allotment
- Applicable cost of acquisition rules
- Holding period for determining STCG or LTCG
- Purchase and bonus share records
Investors should maintain proper documentation of bonus issues and transaction history to calculate capital gains accurately while filing their income tax return.
Tax Planning Strategy 6: Check Buyback Tax Treatment Before Selling Shares
Investors should separately evaluate share buyback transactions because the tax treatment of buyback proceeds may differ from a normal sale of shares through the stock exchange.
A buyback transaction should not automatically be treated in the same manner as a regular share sale. The applicable tax treatment depends on the nature of the transaction, the shareholder category, and the provisions applicable for the relevant tax year.
Before participating in a company buyback, investors should review:
- Whether the transaction is a company buyback or a market sale of shares
- Applicable capital gains provisions
- Impact on overall tax liability
- Reporting requirements while filing the income tax return
Investors should avoid relying on older buyback tax explanations because the tax treatment of buyback proceeds has changed. The applicable provisions should be checked based on the relevant tax year and transaction details before making a decision.
Difference Between Section 111A and 112A
|
Basis |
Section 111A |
Section 112A |
|
Nature of gain |
Short-term capital gain | Long-term capital gain |
| Eligible assets | Specified equity shares, equity-oriented fund units, and business-trust units |
Specified equity shares, equity-oriented fund units, and business-trust units |
|
General holding period |
12 months or less | More than 12 months |
| Rate before 23 July 2024 | 15% |
10% |
|
Rate from 23 July 2024 |
20% | 12.5% |
| Separate exemption threshold | No separate annual threshold |
Aggregate annual threshold of ₹1.25 lakh for qualifying LTCG |
|
STT condition |
Generally required on transfer | Generally required as prescribed on acquisition and transfer |
| Loss treatment | Short-term capital loss may generally be adjusted against eligible STCG or LTCG |
Long-term capital loss may generally be adjusted only against LTCG |
|
ITR reporting |
Schedule Capital Gains | Schedule Capital Gains and Schedule 112A, where applicable |
| Provision under the Income-tax Act, 2025 | Section 196 |
Section 198 |
Read our detailed guide on Short-Term Capital Gain Tax (STCG) and Long-Term Capital Gain Tax on Shares to understand the applicable tax rates, holding periods, exemptions, and reporting requirements.
Example of Tax Calculation under Section 111A
Suppose a taxpayer earns an eligible short-term capital gain of ₹2,00,000 from listed equity shares transferred after 23 July 2024.
Calculation:
₹2,00,000 × 20% = ₹40,000
The base tax under Section 111A would be ₹40,000. Applicable surcharge and cess would be charged separately.
Example of Tax Calculation under Section 112A
Suppose a taxpayer earns eligible long-term capital gains of ₹3,00,000 during the financial year.
Calculation:
- Total LTCG: ₹3,00,000
- Less: Exemption limit: ₹1,25,000
- Taxable LTCG: ₹1,75,000
- Tax at 12.5%: ₹21,875
The base tax under Section 112A would be ₹21,875. Applicable surcharge and cess would be charged separately.
These are simplified examples and do not consider adjustments against the basic exemption limit, loss set-off, rebate, surcharge, cess, or other income.
Read our detailed guide on Capital Gains Tax to understand the tax treatment of short-term and long-term capital gains, applicable rates, exemptions, and reporting requirements.
Before Selling Shares: Tax Planning Checklist
Before selling listed equity shares, investors should review the following:
- Check purchase dates of individual share lots
- Apply FIFO method for demat holdings
- Classify gains as STCG or LTCG
- Verify the ₹1.25 lakh LTCG threshold availability
- Review current-year and brought-forward capital losses
- Check grandfathering benefits for eligible old shares
- Verify tax treatment of bonus shares
- Evaluate buyback transactions separately
- Maintain broker statements and purchase records
- Report capital gains correctly in the applicable ITR schedule
Need Expert Assistance with Capital Gains ITR Filing?
Capital gains from equity shares, mutual funds, and other securities require accurate classification, tax computation, and reporting in the appropriate ITR schedules.
Ebizfiling provides Income Tax Return Filing support for individuals and businesses earning capital gains incomecapital gains capital gains . Our experts can assist with reviewing transaction statements, classifying short-term and long-term gains, computing the applicable tax liability, and reporting the details in the relevant ITR schedules.
Ebizfiling can assist you with:
- Income Tax Return Filing
- Capital gains computation support
- Review of broker and mutual-fund statements
- Income Tax Notice Assistance
- Tax consultation and compliance support
Get professional assistance from Ebizfiling for accurate capital gains reporting and Income Tax Return Filing.
Conclusion
Section 111A and 112A play an important role in determining the tax liability on eligible short-term and long-term capital gains arising from specified equity-related securities. Under the Income-tax Act, 2025, these provisions are renumbered as Section 196 and Section 198, respectively. Taxpayers should carefully verify the asset type, holding period, STT conditions, applicable tax rate, exemption threshold, and ITR reporting requirements before filing their return.
Suggested Reads:
ESOP and RSU Taxation in India 2026
How to Save Tax on Gold Investments
Section 87A Capital Gains in 2026
Frequently Asked Questions
1. What is STCG tax on listed equity in 2026?
Generally 20% where the specified STT conditions are satisfied.
2. What is LTCG tax on listed equity?
Generally 12.5% on aggregate specified equity LTCG exceeding Rs. 1.25 lakh.
3. Can I choose high-cost shares to sell?
Not within a fungible demat holding; FIFO identifies the tax lot.
4. Does Rs. 1.25 lakh exemption apply to every capital gain?
No. It is for specified equity-related LTCG.
5. Can Section 87A remove share STCG/LTCG tax?
Current guidance says the rebate is not available against tax on special-rate income.
6. How are buybacks taxed from 1 April 2026?
The Finance Act 2026 moves buyback consideration to capital-gains treatment under the 2025 Act, with additional rules for promoters.
7. Can NRIs be taxed under Section 111A and 112A?
NRIs may be covered subject to their residential status, the nature and location of the asset, STT conditions, applicable non-resident provisions, and any relief available under the relevant DTAA.
8. Can short-term capital losses be set off against gains taxable under Section 112A?
A short-term capital loss may generally be adjusted against eligible short-term or long-term capital gains. However, a long-term capital loss may generally be adjusted only against long-term capital gains.
9. Which documents should be maintained for Section 111A and 112A transactions?
Taxpayers should maintain broker contract notes, demat statements, mutual-fund statements, purchase records, sale records, and capital gains reports. These documents help support the transactions reported in the Income Tax Return.
10. How can Ebizfiling help with Section 111A and 112A capital gains reporting?
Ebizfiling can assist taxpayers with reviewing investment statements, classifying short-term and long-term gains, applying the relevant tax rates, calculating tax liability, and reporting capital gains in the appropriate Income Tax Return schedules.





ITR filing
Filing of Income Tax return is necessary if you have earned any income. File your ITR with EbizFiling
About Ebizfiling -


Reviews
Nisha Swaroop
11 Oct 2019It was fantastic working with EbizFiling. They are friendly and supportive. Everything done smoothly and on timely basis. I would love to work with them again.
Ratnesh Mishra
19 Nov 2021Awesome work done by this team especially Ms Aishwarya and Mr Deepak....They followed everything on time and service cost was very competitive... Looking forward working with these awesome guys👏👏👏😍
DEEPAK BAGRA
08 Sep 2018I find the service, working approach and commitments very professional. Their progress updates are commendable. I really liked working with them.
September 11, 2026 By Siddhi R
Section 130 of the Income Tax Act: Home Loan Interest Deduction Introduction Buying a residential house property often involves taking a home loan, and the interest paid on such loans can provide tax benefits under certain provisions of the Income […]
September 10, 2026 By Srishti M
12AB and 80G Notice Reply: Documents Required and Response Process Introduction A trust, society, Section 8 company, or other eligible non-profit organisation may receive a notice from the Income Tax Department while its registration or approval application is under examination. […]
September 5, 2026 By Steffy A
Property Acquisition Tax Planning: A Complete Guide Introduction Buying a residential property requires careful financial planning because it involves significant decisions related to taxation, funding, ownership structure, and long-term financial goals. Whether an individual is purchasing a first home or […]