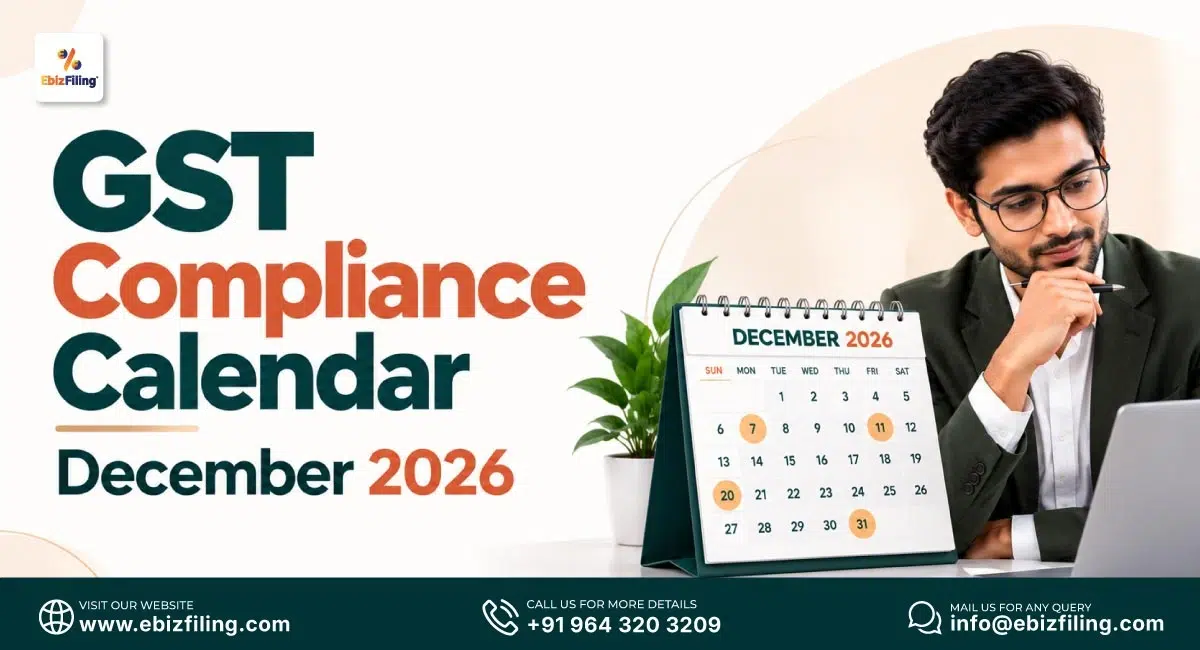
GST Compliance Calendar for December 2026 showing important GST return due dates

GST Compliance Calendar December 2026: Key Due Dates & Filings

Introduction

The GST Compliance Calendar December 2026 covers important GST return filing, tax payment, invoice reporting and annual compliance deadlines applicable during the month. It includes obligations for regular taxpayers, QRMP taxpayers, e-commerce operators, Input Service Distributors, non-resident taxable persons, OIDAR service providers and applicable GST TDS/TCS entities.


December is particularly important for businesses preparing GST annual returns and reconciliation statements for FY 2025-26. Taxpayers should review their annual turnover, previously filed returns, input tax credit records and financial statements to identify applicable filing requirements. Following the GST Compliance Calendar December 2026 can help businesses manage year-end reporting, address reconciliation differences and reduce the risk of late fees, interest and compliance notices.


Quick Insights

  • GSTR-9 and GSTR-9C for FY 2025-26 are generally due by 31 December 2026, subject to applicable turnover thresholds, exemptions and extensions.
  • GSTR-7 and GSTR-8 cover separate GST TDS and TCS reporting obligations for November 2026.
  • Monthly taxpayers must track GSTR-1 and GSTR-3B, while eligible QRMP taxpayers can use the optional IFF for November B2B invoice reporting.
  • QRMP taxpayers must review their November tax payment obligations through Form GST PMT-06, separately from quarterly return filing.
  • December is an important period for reconciling annual turnover, ITC, tax liabilities and financial records before submitting applicable GST annual returns.


Important Due Dates GST Compliance Calendar December 2026


Due Date

Compliance

Form

Period

Applicable To

10/12/2026

GST TDS Return Filing GSTR-7 November 2026 Applicable GST TDS deductors
10/12/2026 GST TCS Statement Filing GSTR-8 November 2026

Applicable e-commerce operators

11/12/2026

Outward Supply Statement GSTR-1 November 2026 Monthly GST taxpayers
13/12/2026 Non-Resident Taxable Person Return GSTR-5 November 2026

Non-resident taxable persons

13/12/2026

Input Service Distributor Return GSTR-6 November 2026 Registered ISDs
13/12/2026 Invoice Furnishing Facility IFF November 2026

QRMP taxpayers opting to use IFF

20/12/2026

Monthly GST Return GSTR-3B November 2026 Regular monthly taxpayers
20/12/2026 OIDAR Services Return GSTR-5A November 2026

Applicable overseas OIDAR suppliers

25/12/2026

QRMP Monthly Tax Payment PMT-06 November 2026 QRMP taxpayers required to deposit tax
31/12/2026 GST Annual Return GSTR-9 FY 2025-26

Registered taxpayers required to file

31/12/2026

GST Reconciliation Statement GSTR-9C FY 2025-26

Taxpayers meeting prescribed criteria


Disclaimer: Dates represent the standard statutory GST compliance schedule. Applicability, exemptions and extensions notified by the Government must be considered. GSTR-9 and GSTR-9C relate to FY 2025-26.
Get Expert Guidance on
GST Compliance & Classification

Simplify GST compliance with expert advisory and accurate HSN/SAC classification.

Find Your HSN/SAC Code

Penalties, Interest and Consequences of GST Non-Compliance

Failure to meet GST compliance requirements may attract late filing fees, interest on unpaid tax, notices and other statutory consequences. The applicable liability depends on the GST return, nature of default, tax amount and relevant provisions of the CGST Act, 2017.


Non-Compliance

Late Fee / Interest

Possible Consequences

Late GSTR-1 Filing

Generally ₹50 per day; ₹20 per day for NIL statements, subject to applicable limits.

May affect recipients’ ITC reporting and subsequent return filing.

Late GSTR-3B Filing

Generally ₹50 per day; ₹20 per day for NIL returns, subject to prescribed limits.

Interest on unpaid tax, notices and return-filing restrictions may apply.

Late GSTR-7 Filing

₹50 per day combined under CGST and SGST/UTGST, capped at ₹2,000 combined.

Outstanding GST TDS obligations may attract further statutory action.

GSTR-8 Non-Compliance

Unpaid GST TCS may attract applicable interest and penalties.

Incorrect reporting or failure to deposit TCS may result in notices or recovery proceedings.

Late GSTR-5, GSTR-5A or GSTR-6

Applicable late fees, interest or penalties depend on the return and nature of default.

Continued non-compliance may result in notices or other statutory action.

Delayed QRMP Tax Payment

Interest generally applies at 18% per annum on the applicable delayed or short-paid tax amount.

Outstanding tax liabilities may attract recovery proceedings.

Late GSTR-9 / GSTR-9C

Late fees under Section 47(2), subject to applicable turnover-based limits and concessions.

The annual return remains incomplete where mandatory GSTR-9C has not been furnished.

Wrongful ITC Claims or Tax Short-Payment

Interest, tax recovery and penalties may apply according to the nature of the default.

Scrutiny, tax demands or recovery proceedings may arise.


Important Notes:

  • Interest on Delayed GST Payment: Generally 18% per annum under Section 50(1), subject to applicable calculation rules and exceptions.
  • Wrongly Availed ITC: Interest under Section 50(3) generally applies where ineligible ITC has been both availed and utilised, as calculated under Rule 88B.
  • Optional IFF: Eligible QRMP taxpayers do not incur an independent late filing fee merely for not using the optional Invoice Furnishing Facility.
  • GSTR-9C Late Fees: Where GSTR-9C is mandatory, late fees are calculated until the complete annual return is furnished. Separate late fees are not imposed independently for GSTR-9 and GSTR-9C for the same delay.
  • Additional Penalties: Penalties depend on the nature of the violation and are not automatically imposed for every delayed GST filing.


Disclaimer: The above rates and consequences are subject to the CGST Act, 2017, applicable GST Rules, government notifications, amendments, waivers and exemptions. Actual liability depends on the taxpayer’s circumstances and relevant statutory provisions.


Stay Prepared for December GST Compliances with Ebizfiling

December brings important GST obligations, including monthly returns, tax payments, ITC reconciliation and annual filings through GSTR-9 and GSTR-9C, where applicable. With different requirements for regular taxpayers, QRMP taxpayers, exporters, e-commerce operators and other registered entities, businesses must identify their applicable filings and review supporting records before submission.


Ebizfiling helps businesses manage their GST requirements through professional support for:

  • GST Registration & Updates: GST Registration and GST Registration Modification for new registrations and changes to registered business details.
  • GST Returns & Tax Payments: GST Return Filing, GSTR-1 Filing and Online GST Payment for applicable reporting and payment obligations.
  • GST Refunds & ITC Review: Assistance with eligible refund applications, refund documentation, input tax credit reconciliation and reporting differences.
  • Export-Related GST Compliance: GST LUT Filing for eligible exporters undertaking zero-rated supplies without payment of integrated tax, subject to applicable conditions.

Use the GST Compliance Calendar December 2026 to review your upcoming obligations, prepare the required documentation and manage GST filings with professional support from Ebizfiling.

Stay GST Compliant
with Expert Assistance

Meet every GST deadline with professional filing and compliance support from Ebizfiling.

Consult our Experts

Conclusion

The GST Compliance Calendar December 2026 highlights important monthly and annual GST obligations, including GSTR-1, GSTR-3B, GST TDS/TCS returns, QRMP payments and applicable GSTR-9 and GSTR-9C filings for FY 2025-26.


Businesses should reconcile their sales records, purchase data, GSTR-2B, ITC claims and tax liabilities before completing the relevant filings. GST annual return requirements must also be assessed according to applicable turnover thresholds, exemptions and government notifications.


For a broader overview of statutory deadlines, explore our Compliance Calendar December 2026 , covering GST, Income Tax, TDS/TCS, PF and ESI, LLP, OPC and Company compliances.


Suggested Reads:

Compliance Calendar FY 2026-27

Compliance Calendar November 2026

GST Compliance Calendar November 2026

TDS and TCS Compliance Calendar December 2026


Frequently Asked Questions


1. Can ITC be claimed when an invoice is missing from GSTR-2B?

ITC should not be claimed merely because the supplier has filed GSTR-1. The recipient must satisfy the applicable Section 16 conditions, including the prescribed communication of invoice details, before availing the credit.


2. Does a GSTR-1 and GSTR-3B liability mismatch automatically create a GST demand?

No. A qualifying mismatch may generate Form GST DRC-01B. The taxpayer can pay the shortfall through DRC-03, explain the difference, or use both options as applicable. Failure to respond can affect subsequent GSTR-1 or IFF filing.


3. What happens when a recipient rejects a supplier's credit note in IMS?

Where a credit note is rejected in IMS, the corresponding supplier liability can be added in the GSTR-3B of a subsequent tax period. GSTN also advises correcting an incorrect invoice through amendment rather than issuing a credit note merely to rectify invoice errors.


4. Is ITC reversal proportionate when only part of an invoice remains unpaid for 180 days?

Yes. Rule 37 operates proportionately. If only part of the value of supply and tax remains unpaid beyond the prescribed period, only the ITC attributable to that unpaid portion is subject to reversal, along with applicable interest.


5. Can ITC be retained if the supplier files GSTR-1 but does not file the corresponding GSTR-3B?

Not indefinitely. Rule 37A requires reversal in the prescribed circumstances where the supplier fails to furnish the corresponding return. The recipient may re-avail the credit after the supplier files the return, subject to the applicable conditions.


6. Can the recipient's GSTIN be corrected through GSTR-1A?

No. GSTN specifically provides that the recipient’s GSTIN cannot be amended through GSTR-1A. The correction must be made through the applicable subsequent GSTR-1 amendment facility within the permitted time limit.


7. What does an excess ITC reclaim in the Electronic Credit Reversal and Re-claimed Statement indicate?

It generally indicates that the ITC reported as reclaimed exceeds the reversal balance available in the statement. The taxpayer should reconcile earlier reversals, current-period reversals and reclaims before reporting the amount in GSTR-3B.


8. Can GSTR-1 be filed when Table 12 HSN values do not match outward-supply tables?

In applicable cases, yes. GSTN may display a warning where the taxable value or tax amount reported in Table 12 does not reconcile with the relevant outward-supply tables. The taxpayer may be permitted to proceed after accepting the warning, but remains responsible for correct HSN/SAC and tax reporting.


9. How can Ebizfiling assist with GSTR-2B and purchase-register mismatches?

Ebizfiling can assist with invoice-level reconciliation to identify missing invoices, amendments, duplicate credits, incorrect GSTINs and potentially ineligible ITC, and help determine whether supplier correction, ITC reversal or another return adjustment is required.


10. How can Ebizfiling assist when GSTR-9 turnover does not match financial statements?

Ebizfiling can assist with reconciling GSTIN-wise turnover, credit notes, debit notes, advances, exempt supplies, amendments and prior-period adjustments against accounting records before the annual return is prepared.

About Ebizfiling -

EbizFiling is a concept that emerged with the progressive and intellectual mindset of like-minded people. It aims at delivering the end-to-end corporate legal services 0f incorporation, compliance, advisory, and management consultancy services to clients in India and abroad in all the best possible ways.
 
To know more about our services and for a free consultation, get in touch with our team on  info@ebizfiling.com or call 9643203209.
 
Ebizfiling

Author: srishti

Srishti Mukherjee is an Advocate, Legal Researcher, and Legal Content Writer at Ebizfiling, with practical courtroom experience in civil, criminal, and revenue matters before Trial Courts and High Courts. She holds an LL.M. in Constitutional Law and Criminal Law, combining her academic background with hands-on litigation experience, legal drafting, and statutory interpretation. At Ebizfiling, Srishti researches and writes on corporate law, Income Tax, GST, Intellectual Property Rights (IPR), business registration, and regulatory compliance. Her professional interests extend to company law, taxation, and emerging legal developments, where she applies her legal research skills to understand statutory provisions, compliance procedures, and their practical implications for businesses and individuals. Her writing reflects a research-oriented approach supported by practical legal experience. She focuses on simplifying complex legislation, regulatory requirements, filing procedures, and legal documentation into clear, structured, and accessible content. Through her articles, she aims to help startups, businesses, professionals, and taxpayers better understand legal obligations and make informed compliance decisions.

Follow Author

Leave a Reply

Your email address will not be published. Required fields are marked *

  • Rating

Hi, Welcome to EbizFiling!

Hello there!!! Let us know if you have any Questions.

Thank you for your message.

☎
whatsapp