


-
September 11, 2026
-
BySiddhi R
Section 80EE of the Income Tax Act: Eligibility & Deduction
Introduction
Buying a residential property through a home loan can provide certain tax benefits to eligible taxpayers. Section 80EE of the Income Tax Act allows eligible individual taxpayers to claim an additional deduction on interest paid or payable towards a home loan, subject to specific conditions prescribed under the Income Tax Act.
Under the Income-tax Act, 2025, the provisions relating to this deduction have been renumbered as Section 130. The benefit available under the provision continues to provide an additional deduction for eligible individuals on home loan interest, subject to the applicable conditions.
This provision was introduced to provide additional support to first-time home buyers by allowing an extra deduction of up to ₹50,000 per tax year. Under the Income-tax Act, 1961, Section 80EE operated in addition to the eligible home loan interest deduction under Section 24(b). Under the Income-tax Act, 2025, the corresponding house-property interest deduction is contained in Section 22. However, the same interest amount cannot be claimed twice.
Key Highlights
- Additional deduction of up to ₹50,000 per tax year is available on home loan interest for eligible individuals.
- Only individual taxpayers who are first-time home buyers can claim the benefit under Section 80EE.
- The home loan must have been sanctioned between 1 April 2016 and 31 March 2017 to qualify for the deduction.
- The residential property value should not exceed ₹50 lakh and the loan amount should not exceed ₹35 lakh.
- Section 80EE/130 provides an additional deduction, but the same interest cannot be claimed twice.
- Section 80EE/Section 130 deduction is not available under the default new tax regime under Section 202.
What is Section 80EE of the Income Tax Act?
Section 80EE of the Income Tax Act provides an additional deduction for interest paid or payable on a home loan taken by an individual for purchasing a residential property. The deduction can be claimed by eligible taxpayers until the repayment of the home loan, provided all applicable conditions are satisfied.
The maximum deduction available under this provision is ₹50,000 per tax year. This benefit is available in addition to the deduction allowed for home loan interest under Section 24(b).
To understand other eligible deductions and how they reduce taxable income, read our complete guide on Tax Deduction in India.
However, this deduction is not available for all new home loans. The home loan must have been sanctioned between 1 April 2016 and 31 March 2017 to qualify for this benefit.
Eligibility Criteria for Section 80EE Deduction
Only individual taxpayers can claim the Section 80EE deduction. Businesses, companies, and other entities are not eligible to claim this benefit.
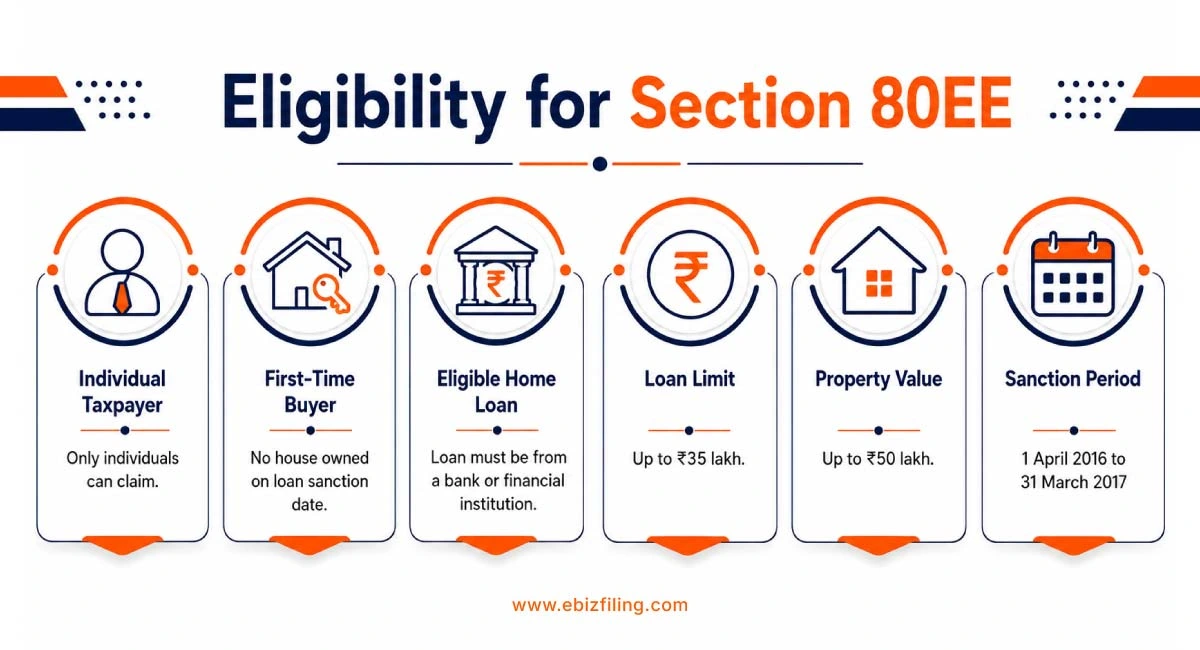
The following conditions must be fulfilled to claim the deduction:
- The taxpayer must be an individual.
- The taxpayer must be a first-time home buyer.
- The taxpayer should not own any residential house property on the date when the home loan is sanctioned.
- The home loan must be taken from a bank or eligible financial institution.
- The loan amount sanctioned should not exceed ₹35 lakh.
- The value of the residential property should not exceed ₹50 lakh.
- The loan must have been sanctioned between 1 April 2016 and 31 March 2017.
The deduction is available on an individual basis. Therefore, eligibility depends on whether the taxpayer satisfies the required conditions personally.
Persons Not Eligible to Claim Section 80EE Deduction
Since Section 80EE of the Income Tax Act is specifically available for individual taxpayers, certain persons and entities cannot claim this deduction.
The following cannot claim the benefit:
- Hindu Undivided Family (HUF)
- Companies
- Partnership firms
- Limited Liability Partnerships (LLPs)
- Association of Persons (AOP)
- Trusts
The provision is designed specifically for eligible individuals purchasing their first residential property through a qualifying home loan.
Conditions to Claim Section 80EE Home Loan Deduction
To claim the Section 80EE home loan deduction, taxpayers must ensure that all prescribed conditions are met. The deduction is available only when the home loan and property details satisfy the requirements under the Income Tax Act.
Important conditions include:
- The residential property value should not exceed ₹50 lakh.
- The sanctioned home loan amount should not exceed ₹35 lakh.
- The loan should be approved by a financial institution as defined under the provision or housing finance company.
- The taxpayer should not own another residential property when the loan is approved.
- The deduction should be claimed only for eligible interest payments.
Taxpayers should maintain proper records of loan approval documents, interest certificates, and property-related documents while claiming the deduction.
Deduction Limit Under Section 80EE
The maximum deduction available under Section 80EE of the Income Tax Act is ₹50,000 per tax year.
This deduction is allowed only for interest paid or payable on the eligible home loan. It can be claimed in addition to other available deductions, including:
- Deduction under Section 24(b) for home loan interest.
- Deduction under Section 80C for eligible principal repayment, subject to applicable limits.
- The taxpayer cannot claim the same interest amount twice under different sections of the Income Tax Act.
Benefits of Section 80EE for First-Time Home Buyers
The primary objective of Section 80EE of the Income Tax Act is to provide additional tax relief to individuals purchasing their first residential property.
Some important benefits include:
- Additional deduction of up to ₹50,000 on home loan interest.
- Reduced overall tax liability for eligible taxpayers.
- Extra benefit over the deduction available under Section 24(b).
- Financial support for individuals purchasing their first home.
- Long-term tax savings during the home loan repayment period.
This provision can help eligible taxpayers manage the financial burden associated with purchasing a residential property.
Claim Tax Benefits Correctly with Ebizfiling Support
Understanding and claiming deductions under the Income Tax Act requires proper knowledge of eligibility conditions and documentation requirements. Ebizfiling helps individuals and businesses with accurate tax compliance support, including income tax filing, deduction guidance, and tax-related assistance.
Our experts can help you understand applicable deductions, review your documents, and ensure that your tax return is prepared correctly while considering available benefits under the Income Tax Act.
With Ebizfiling, you can get support for:
- Income tax return filing and compliance assistance.
- Guidance on eligible deductions and tax benefits.
- Review of home loan interest and other tax-related documents.
- Assistance in preparing accurate tax filings.
- Expert support for resolving income tax-related queries.
For personalised guidance on deductions and home loan tax benefits, you can use Ebizfiling’s Tax Consultancy Services to understand the applicable provisions and plan your tax filing correctly.
Conclusion
Section 80EE of the Income Tax Act provides home loan tax benefits that can reduce the financial burden of purchasing a residential property. Eligible individuals who meet the required conditions can claim an additional deduction of up to ₹50,000 under this provision.
With the introduction of the Income-tax Act, 2025, the existing provision of Section 80EE has been renumbered as Section 130 of the Income Tax Act. Taxpayers should refer to the applicable provisions based on the relevant assessment year while claiming deductions for home loan interest.
Before claiming the benefit, taxpayers should verify loan sanction details, property value, ownership conditions, and other requirements. Proper understanding of eligibility criteria ensures accurate tax filing and helps taxpayers utilise available deductions effectively.
Frequently Asked Questions
1. Who can claim deduction under Section 80EE of the Income Tax Act?
Only individual taxpayers who meet the specified eligibility conditions can claim the benefit under Section 80EE of the Income Tax Act. The taxpayer must be a first-time home buyer and should not own any residential property on the date of home loan sanction.
2. What is the maximum amount available under Section 80EE deduction?
The maximum benefit available under the Section 80EE deduction is ₹50,000 per tax year. This deduction is available on eligible home loan interest payments and can be claimed in addition to other applicable housing loan deductions, subject to conditions.
3. Can I claim Section 80EE home loan deduction if my loan was sanctioned after 31 March 2017?
No. The home loan deduction under Section 80EE of the Income Tax Act is available only for eligible home loans sanctioned between 1 April 2016 and 31 March 2017. Loans sanctioned after this period do not qualify for this specific deduction.
4. Is Section 80EE available along with Section 24(b) deduction?
Yes. Under Section 80EE of the Income Tax Act, both deductions can be claimed together if the taxpayer fulfils the required conditions. Section 24(b) provides deduction for home loan interest, while Section 80EE provides an additional deduction of up to ₹50,000.
5. Can a joint home loan holder claim deduction under Section 80EE?
A joint home loan holder can claim the additional deduction under Section 80EE only if they individually satisfy all eligibility requirements. Joint ownership or joint loan does not automatically make a person eligible for the deduction.
6. Can Section 80EE deduction be claimed for a rented property?
Section 80EE can be claimed in addition to the eligible deduction under Section 24(b). However, the same portion of home loan interest cannot be claimed twice under both provisions. Under the Income-tax Act, 2025, taxpayers should also consider the house-property interest deduction under Section 22 and the tax regime selected.
7. Can HUF claim deduction under Section 80EE?
No. Section 80EE of the Income Tax Act eligibility criteria specify that only individual taxpayers can claim this deduction. HUFs, companies, firms, LLPs, and trusts are not eligible for this benefit.
8. What documents are required to claim Section 80EE deduction?
To claim the Home loan interest deduction under the Income Tax Act, taxpayers should maintain documents such as home loan sanction letters, interest certificates from lenders, property documents, and repayment records.
9. How can Ebizfiling help with Section 80EE deduction and income tax filing?
Ebizfiling helps taxpayers understand eligibility conditions, organise required documents, and complete accurate income tax filing. Our experts assist with reviewing available deductions, including the Section 80EE deduction, and provide support for tax compliance requirements.
10. Why should taxpayers verify Section 80EE eligibility criteria before claiming the deduction?
Checking the Section 80EE eligibility criteria helps taxpayers avoid incorrect claims and ensures compliance with Income Tax Act requirements. Loan sanction date, property value, loan amount, and ownership status should be verified before claiming the benefit.





Income Tax Return
Filing of Income Tax return is necessary if you have earned any income. File your ITR with EbizFiling.
About Ebizfiling -


Reviews
Kalla swathi
09 Apr 2022Excellent service indeed.. I appreciate the entire team for incorporating my company very well
Karthik
05 Apr 2019Awesome Service! I am very happy with the way the process is being handled. Snehal also followed up constantly to ensure that the items are completed on time successfully. Thanks for your service.
Kavita Pawar
21 Jun 2018I would surely give them 5 stars for their Services, Staff, and Pricing!
September 17, 2026 By Riyansh S
Defective Return Notice: Resolve Schedule BS & PL Errors Introduction Receiving a Defective Return Notice from the Income Tax Department means that the filed Income Tax Return (ITR) contains incomplete, inconsistent, or incorrect information that requires correction. Such notices are […]
September 16, 2026 By Riyansh S
Section 87A Capital Gains in 2026: The Rs. 12 Lakh Trap Explained Introduction “No tax up to Rs. 12 lakh” is useful shorthand for the new tax regime, but it is not a blanket exemption. For AY 2026-27, an eligible […]
September 12, 2026 By Srishti M
Form 10B and Form 10BB Audit Requirements for Charitable Trusts Introduction One of the important compliance obligations for eligible charitable trusts and institutions is furnishing the prescribed audit report. However, many trust administrators face confusion regarding Form 10B and 10BB […]