
-
September 24, 2026
-
BySiddhi R
Form 10BD and Section 80G: Key Differences and New 2026 Rules
Introduction
Form 10BD and Section 80G relate to charitable donations and tax deductions but serve different purposes. Under the earlier Income-tax Act, 1961, Form 10BD was filed by eligible organizations to report donations, while Form 10BE was issued to donors. From 1 April 2026, the corresponding donation-reporting framework operates through Form 113 and Form 114 under the Income-tax Act, 2025 and Income-tax Rules, 2026, while the related deduction provisions are covered under Section 133.
In this blog, we will explain the key differences between Form 10BD and Section 80G, their purpose, filing requirements, and the latest changes under the Income-tax Act, 2025.
Key Highlights
- Form 10BD and Section 80G served different purposes under the earlier tax framework.
- Form 10BD was filed by eligible NGOs and institutions to report donations.
- Form 10BE was the certificate issued to donors for eligible donation claims.
- Form 10BD due date was 31 May following the relevant financial year.
- From 1 April 2026, Form 10BD and Form 10BE were replaced by Form 113 and Form 114.
What is Form 10BD?
Form 10BD was a statement of donations required to be filed by eligible trusts, NGOs, institutions, and other reporting entities under the earlier Income-tax Act, 1961 framework.
Its purpose was to provide the Income Tax Department with details of donations received and information relating to the respective donors. Form 10BD was required to be filed electronically. If no donation was received during the relevant financial year, Form 10BD was not required to be filed.
The Form 10BD due date was 31 May immediately following the end of the financial year in which the donation was received. After filing Form 10BD, the organization was required to issue Form 10BE to eligible donors by the same date.
Therefore, Form 10BD was not a certificate furnished to the donor. It was primarily a donation reporting statement filed by the organization.
What is Section 80G?
Section 80G allowed taxpayers to claim deductions for donations made to specified funds, charitable institutions, and other eligible organizations, subject to prescribed conditions.
Under the earlier framework, a donor generally received a Form 10BE certificate from the eligible organization after the organization reported the donation through Form 10BD.
From 1 April 2026, the corresponding deduction provisions are contained in Section 133 of the Income-tax Act, 2025. Section 133 provides a 100% deduction for certain specified donations and a 50% deduction for certain other eligible donations, subject to the prescribed conditions, limits, and applicable adjusted gross total income restrictions.
What is Form 10BE?
Form 10BE was the donation certificate issued to donors under the earlier framework.
Once an eligible organization filed Form 10BD, it could generate Form 10BE containing details of the organization, donor, and donation. The certificate helped the donor support the deduction claimed for an eligible donation.
The due date for issuing the Form 10BE certificate was 31 May immediately following the financial year in which the donation was received.
This distinction is important because Form 10BD was filed by the organization, while Form 10BE was issued to the donor.
Difference Between Form 10BD and Section 80G
Form 10BD and Section 80G are not two alternative forms serving the same purpose. Form 10BD was a reporting statement, whereas Section 80G dealt with tax deductions available on eligible donations.
|
Criteria |
Form 10BD |
Section 80G |
|
Purpose |
Reporting details of donations received |
Providing tax deduction for eligible donations |
|
Applicable to |
Eligible trusts, NGOs, institutions, and other reporting entities |
Eligible donors and approved charitable organizations |
|
Filed by |
Donee organization |
There was no separate “Section 80G” to be filed by the donor |
|
Donor certificate |
Form 10BE was generated after reporting |
Form 10BE supported the donor’s eligible deduction |
|
Due date |
31 May following the relevant financial year |
No separate due date for a “Section 80G” certificate |
|
Tax deduction |
Form 10BD itself did not provide a deduction |
Eligible donations could qualify for deduction subject to applicable conditions |
|
Current 2026 form |
Form 113 for Tax Year 2026-27 onward |
Donation deduction is now governed by Section 133 |
Form 10BD and Form 10BE Under the New 2026 Rules
An important update applies from 1 April 2026. The Income-tax Act, 2025, came into force from this date and introduced new numbering for several forms and provisions. Organizations familiar with Form 10BD and Section 80G should understand how the new framework changes donation reporting and deduction-related compliance.
Under the Income-tax Rules, 2026:
Form 113 and Form 114 are prescribed under Section 354(1) of the Income-tax Act, 2025, while the tax deduction available to eligible donors is governed by Section 133.
- Form 10BD is now Form 113
- Form 10BE is now Form 114
- Form 113 is the statement containing details of donations received by a registered non-profit organization.
- Form 114 is the donation certificate for the donor.
- Form 113 must be filed before 31 May of the following tax year following the relevant financial year. Form 114 is the donation certificate furnished to donors under the new framework. It is generally generated based on donation details reported through Form 113, subject to the prescribed filing mechanism.
Form 113 is required to be submitted electronically through the Income Tax e-Filing portal.
How Do Form 10BD and Section 80G Work Together?
Donors do not have to choose between Form 10BD and Section 80G.
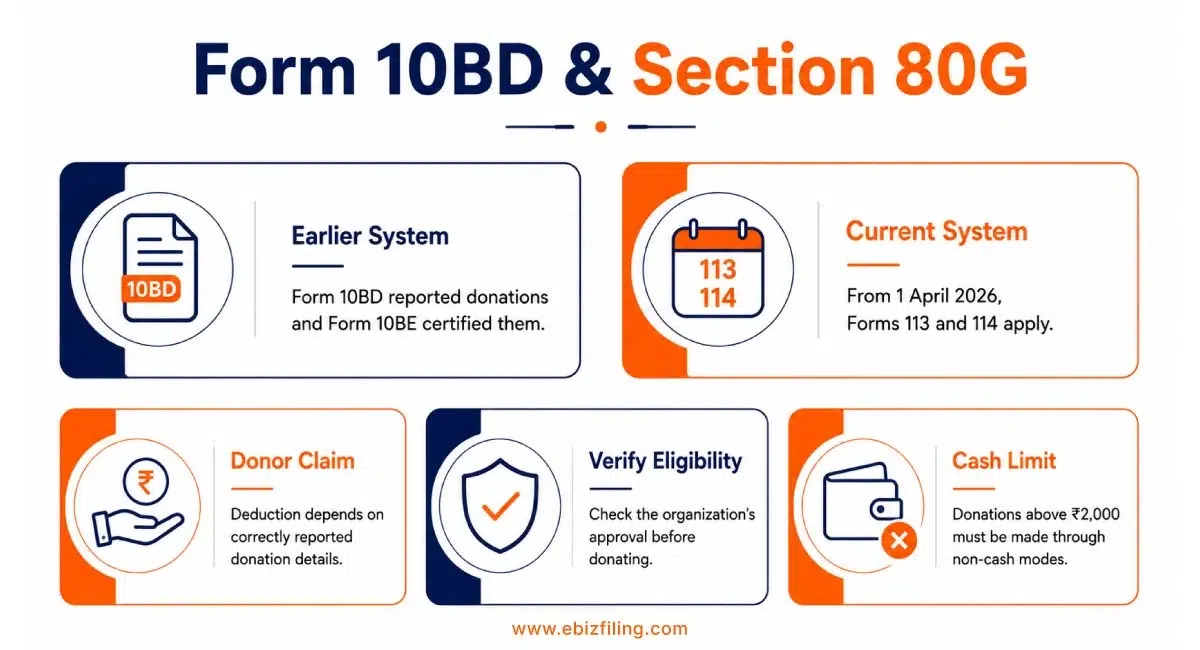
Under the earlier system, an eligible organization receiving donations reported them through Form 10BD. After filing Form 10BD, the organization issued Form 10BE to the donor. The donor could then use the relevant donation details while claiming the applicable tax deduction.
Under the current system from 1 April 2026, registered non-profit organizations report eligible donations through Form 113, and the corresponding donation certificate is provided through Form 114.
For donations covered by Section 133 of the Income-tax Act, 2025, the donor’s deduction claim for donations to specified eligible institutions is linked to the donation information furnished by the institution to the prescribed authority.
Donors should therefore verify that the organization is eligible for the relevant deduction and ensure that their donation details are correctly reported.
Important Point About Cash Donations
Under the current Section 133, a deduction for a donation exceeding ₹2,000 is allowed only when the payment is made through a mode other than cash.
Therefore, donors making larger contributions should use an eligible non-cash payment method if they intend to claim the applicable tax deduction.
Ebizfiling Support for NGO Donation Reporting
Ebizfiling helps NGOs, trusts, and charitable organizations manage donation-related compliance with expert support.
- Form 113 Filing: Assistance with reporting donation and donor details under the current framework.
- Form 114 Support: Guidance for generating and furnishing donation certificates to donors.
- Legacy Form 10BD and 10BE Support: Help with earlier-period donation reporting and related correction requirements.
- NGO Compliance: Support with donation reporting, documentation, registration-related requirements, and applicable tax compliance.
Ebizfiling helps organizations understand both earlier Form 10BD and Section 80G requirements and the applicable compliance framework under the new rules.
Conclusion
The key difference between Form 10BD and Section 80G lies in their purpose. Form 10BD was used by eligible charitable organizations to report donations, while Section 80G dealt with tax deductions available to donors, and Form 10BE was the certificate issued to them. From 1 April 2026, Form 10BD and Form 10BE have been replaced by Form 113 and Form 114, while the related deduction provisions are now covered under Section 133 of the Income-tax Act, 2025. Understanding these changes helps organizations report donations correctly and donors claim eligible tax benefits.
Frequently Asked Questions
1. What happens if donation details in Form 10BD do not match the donor’s PAN?
Incorrect PAN or donor details can create problems when the donor claims the eligible deduction. The organization should verify donor information carefully and make corrections through the permitted filing process where applicable.
2. Can Form 10BE be issued if Form 10BD was not filed?
Under the earlier framework, Form 10BE was generated based on the donation details reported through Form 10BD. Therefore, the required Form 10BD filing had to be completed before the system-generated Form 10BE could be downloaded and issued.
3. Was Form 10BD required when an NGO received no donations?
No. If an eligible organization did not receive any reportable donations during the relevant financial year, Form 10BD for NGOs was generally not required for that year.
4. What should a donor do if Form 10BE shows the wrong donation amount?
The donor should contact the charitable organization and request correction of the reported donation details. The organization may need to correct its donation statement so that the corresponding Form 10BE for donors reflects accurate information.
5. Can a donor claim a deduction if the organization forgets to report the donation?
A donor’s deduction claim may be affected if the eligible organization does not correctly report the donation to the prescribed authority. Donors should therefore verify that their donation details have been properly recorded and obtain the applicable donation certificate.
6. Can Form 10BD be corrected after filing?
Yes. Under the earlier framework, corrections to Form 10BD could be made through the prescribed process where permitted. Under the current framework, organizations can file a revised Form 113 to correct, revise, or delete previously reported donation details, subject to the applicable filing procedure.
7. Does the ₹2,000 cash limit apply to donations under Section 133?
Yes. Under Section 133 of the Income-tax Act, 2025, a donation exceeding ₹2,000 made in cash is not eligible for deduction. Donors who wish to claim the applicable tax deduction should make donations above ₹2,000 through an eligible non-cash payment mode.
8. What should organizations do with Form 10BD due dates after 1 April 2026?
The earlier Form 10BD due date applied under the previous framework. From 1 April 2026, organizations must follow the current Form 113 reporting requirements and applicable deadlines under the Income-tax Rules, 2026.
9. Can Ebizfiling help correct errors in Form 10BD or donation reporting?
Yes. Ebizfiling can assist NGOs and charitable organizations with reviewing donation details, Form 10BD filing related requirements, documentation, and applicable correction procedures. For current periods, the relevant Form 113 requirements should also be considered.
10. How can Ebizfiling help organizations moving from Form 10BD and Section 80G to the new rules?
Ebizfiling can help charitable organizations understand the transition from Form 10BD and Section 80G related compliance to the current framework, including Form 113, Form 114, donation reporting, and related Section 133 requirements.

File Income Tax Returns
Filing of Income Tax return is necessary if you have earned any income. File your ITR with EbizFiling at INR 1199/- only.
About Ebizfiling -
Reviews
Akshay Sharma
18 Apr 2022I took a TM service for my Tea Brand, wonderful service with humble staff, and provided solutions on time. Recommended for all
Harshit Gamit
19 Apr 2018My GST process was made easier with Ebizfiling. I really appreciate the hard work by your team. Keep up the same in the future. Good Luck!
Peoplestrat
16 Mar 2019Well coordinated effort to file our first GST return. Thanks to the team.
September 26, 2026 By Srishti M
Company Compliance Calendar October 2026: Key Due Dates & Filings Introduction The Company Compliance Calendar October 2026 provides an overview of important statutory and regulatory compliances that companies need to track during the month under the Companies Act, 2013 and […]
September 26, 2026 By Srishti M
TDS and TCS Compliance Calendar October 2026: Compliance Guide Introduction The TDS and TCS Compliance Calendar October 2026 provides an overview of important tax deduction and collection obligations applicable to deductors and collectors. It helps businesses, government offices and other […]
September 25, 2026 By Srishti M
OPC Compliance Calendar October 2026: Important Filings & Requirements Introduction The OPC Compliance Calendar October 2026 highlights the key statutory obligations that One Person Companies should monitor during the month. October primarily includes compliance requirements related to financial statement filing […]