
80G Approval Notice : How to Respond and Avoid Rejection
Introduction
Charitable trusts, societies, and other eligible institutions may receive an 80G Approval Notice from the Income Tax Department while their application for approval under Section 80G is being processed.
An 80G Approval Notice is generally issued when the Income Tax Department requires additional information, clarification, or supporting documents to verify the details submitted by the applicant. Such a notice provides an opportunity to submit the required information before the application is considered further.
Organisations applying for 80G approval should carefully review the queries mentioned in the notice and submit a point-wise response along with relevant documents within the prescribed timeline.
Approval under Section 80G is granted after examination of the application, documents, and compliance details submitted by the organisation. Therefore, a proper response helps the authority evaluate the application based on complete information.
This article explains the meaning of an 80G Approval Notice, reasons for receiving it, documents required, and the process to respond.
Quick Insights
- An 80G Approval Notice is issued when the Income Tax Department requires additional details while examining an application under Section 80G.
- Applications relating to 80G approval may require filing of Form 10A or Form 10AB depending on the nature of the application.
- The department may ask for details related to registration, charitable activities, financial records, and previous approvals.
- Applicants should submit a complete response within the deadline mentioned in the notice.
- Submission of a reply does not automatically result in approval, as the application is decided after verification of eligibility and compliance requirements.
What is an 80G Approval Notice?
An 80G Approval Notice is a communication issued by the Income Tax Department to a trust, institution, society, or other eligible organisation seeking approval under Section 80G of the Income-tax Act.
Section 80G approval enables eligible donors to claim deductions for donations made to approved institutions, subject to the conditions prescribed under the Income-tax Act.
For obtaining registration or approval under applicable provisions, eligible organisations are required to submit applications through the prescribed forms along with relevant details and documents. Depending on the type of application, the organisation may be required to file Form 10A or Form 10AB.
During the verification process, the Income Tax Department may require additional clarification regarding:
- Objectives of the organisation
- Registration details
- Activities carried out
- Financial records
- Compliance history
- Supporting documents submitted with the application
In such situations, the department may issue an 80G Approval Notice requesting further details.
Organisations can also review the process of obtaining 80G registration to understand the approval requirements and compliance conditions.
Why Does an Organisation Receive an 80G Approval Notice?
An organisation may receive an 80G Approval Notice for several reasons, including:
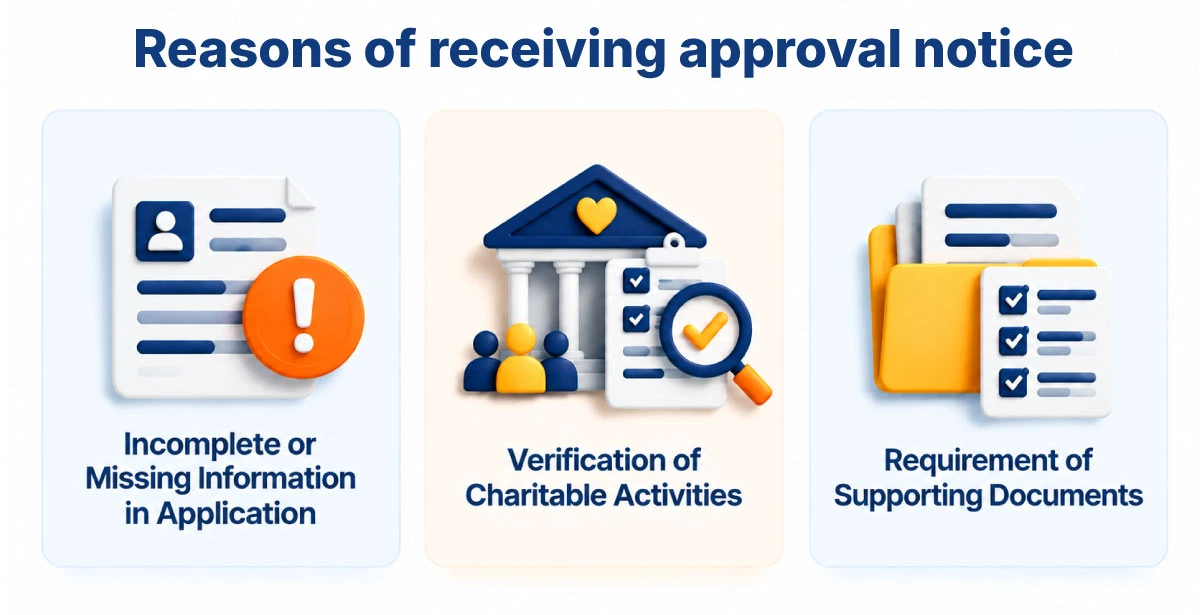
1. Incomplete or Missing Information in Application
The Income Tax Department may issue a notice if the application requires additional clarification or certain information is incomplete.
This may include:
- Missing registration details
- Clarification regarding organisational objectives
- Incomplete activity details
- Additional information required for verification
The applicant should review each query mentioned in the notice and provide a specific response.
2. Verification of Charitable Activities
The department may examine whether the activities performed by the organisation are consistent with its stated objectives.
The applicant may be required to provide details such as:
- Nature of charitable activities conducted
- Details of beneficiaries
- Activity reports
- Supporting evidence of activities performed
The purpose of such verification is to assess whether the organisation satisfies the applicable conditions for approval.
3. Requirement of Supporting Documents
An 80G Approval Notice may request documents required for verification of eligibility and compliance.
Commonly requested documents include:
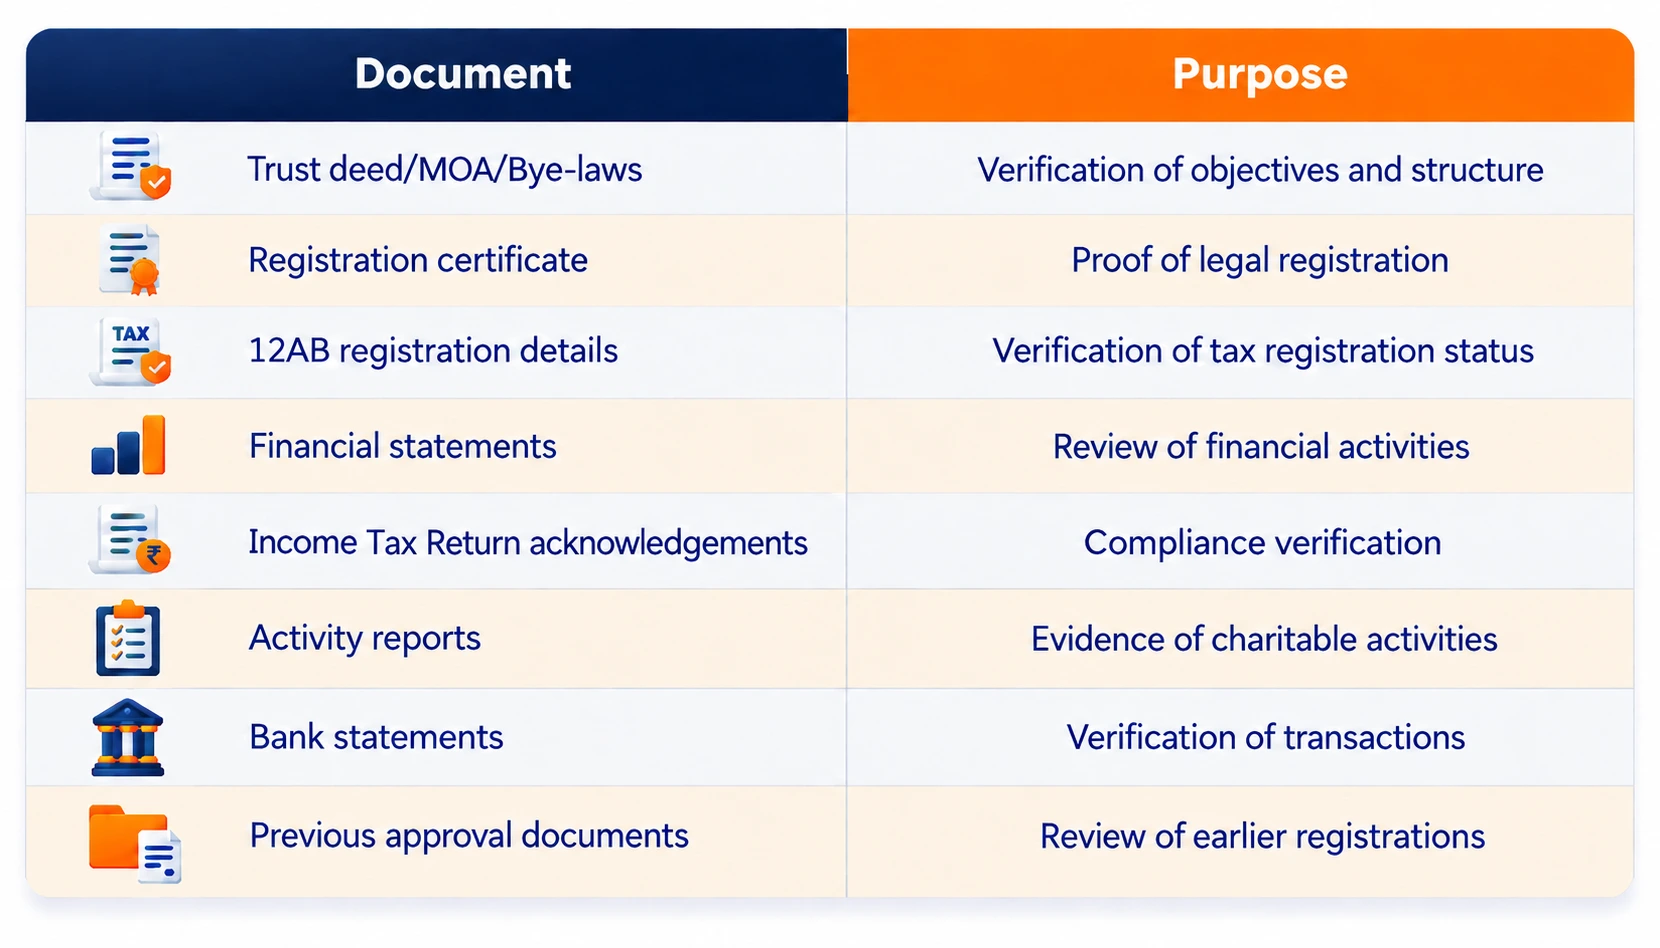
Organisations can also refer to the process of 12AB registration, as 12AB and 80G approvals are commonly associated with charitable institutions.
Final Opportunity Mentioned in an 80G Approval Notice
In certain cases, an 80G Approval Notice may provide the applicant with a final opportunity to submit the required information or documents before the application is decided.
Such notices generally mention:
- Date by which the response must be submitted
- Details or documents required
- Mode of submission
- Consequences of non-submission
The applicant should ensure that the response is submitted within the specified timeline. If no response is submitted, the authority may proceed with the application based on the information available on record.
A final opportunity does not guarantee approval. The application continues to be examined based on the details and documents submitted by the applicant.
Documents Required for Reply to an 80G Approval Notice
The documents required for responding to an 80G Approval Notice depend on the specific queries raised by the Income Tax Department. The applicant should provide only the relevant documents requested in the notice along with supporting explanations.
Common documents that may be required include:
|
Document |
Purpose |
|
Copy of 80G application acknowledgement |
Verification of application submission |
| Form 10A/Form 10AB acknowledgement, where applicable |
Verification of filing details |
|
Trust deed, MOA, or bye-laws |
Verification of objectives and activities |
| Registration certificate |
Proof of legal existence |
|
12AB registration details |
Verification of applicable tax registration |
| Financial statements |
Review of financial activities |
|
Income Tax Return acknowledgements |
Verification of compliance |
| Activity reports |
Evidence of charitable activities carried out |
|
Bank statements |
Verification of financial transactions |
| Previous approval or rejection documents, if applicable |
Review of earlier proceedings |
The organisation should ensure that the information provided in the response matches the details available in its registration documents, financial records, and previous filings.
For organisations that require assistance with charitable entity compliance, understanding the process of trust registration in India can help ensure proper documentation and regulatory compliance.
How to Respond to an 80G Approval Notice?
An applicant receiving an 80G Approval Notice should carefully review the queries raised by the Income Tax Department and prepare a complete response. The general process includes the following steps:
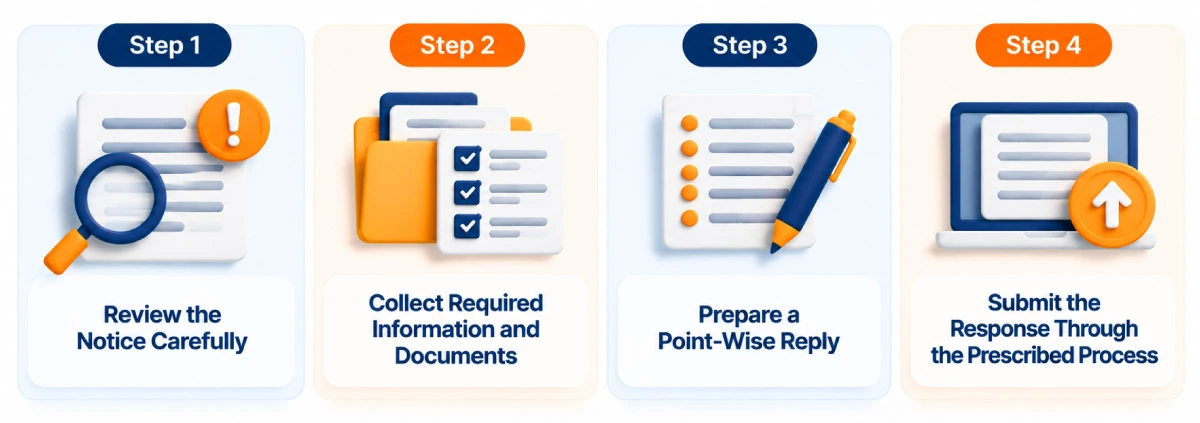
Step 1: Review the Notice Carefully
The organisation should first examine the notice details, including:
- Notice reference number
- Application details
- Queries raised by the department
- Documents requested
- Response submission deadline
A proper understanding of the notice helps in preparing an accurate and complete reply.
Step 2: Collect Required Information and Documents
After reviewing the notice, the organisation should arrange the required documents and information.
The response should be supported by relevant records such as:
- Registration documents
- Financial statements
- Activity details
- Previous approval documents
Other supporting evidence requested in the notice
Step 3: Prepare a Point-Wise Reply
The response to an 80G Approval Notice should address every query separately.
A proper reply generally includes:
- Reference to the notice received
- Response to each query raised
- Explanation wherever clarification is required
- Supporting documents as attachments
A point-wise response helps the Income Tax Department review the submitted information effectively.
Step 4: Submit the Response Through the Prescribed Process
The response should be submitted through the Income Tax e-filing portal or through the method specified in the notice.
After submission, the applicant should maintain:
- Copy of submitted response
- Submission acknowledgement
- Supporting documents filed with the reply
What Happens If You Do Not Respond to an 80G Approval Notice?
If the applicant does not submit the required details within the prescribed timeline, the Income Tax Department may proceed based on the information available on record.
Possible outcomes may include:
- Further delay in processing the application
- Decision based on available information
- Disposal of the application due to non-submission of required details
Therefore, timely submission of a response to an 80G Approval Notice is important to ensure that the application is considered with complete information.
Difference Between 12AB Registration and 80G Approval
While both 12AB registration and 80G approval relate to charitable organisations, they serve different purposes.
|
12AB Registration |
80G Approval |
|
Provides registration benefits to eligible charitable organisations |
Enables eligible donors to claim deduction on qualifying donations |
| Relates to exemption provisions available to eligible institutions |
Relates to tax deduction benefits available to donors |
|
Required for organisations seeking applicable income tax exemption benefits |
Required for organisations seeking approval for donor deduction benefits |
Organisations applying for charitable tax registrations should understand both requirements. You can also refer to the detailed process of 12AB and 80G notice reply for guidance on responding to related Income Tax communications. Organisations seeking tax benefits for charitable activities should also understand the compliance requirements under Section 8 company registration where applicable.
Important Points While Replying to an 80G Approval Notice
While submitting a response to an 80G Approval Notice, organisations should keep the following points in mind:
- Submit the response within the deadline mentioned in the notice.
- Provide complete and accurate information.
- Attach only relevant supporting documents.
- Ensure consistency between the reply and existing records.
- Maintain proof of submission for future reference.
- Review all details before final submission.
The Income Tax Department examines the application based on the information and documents submitted. Therefore, a clear and properly supported response helps in presenting the organisation’s compliance position.
Need Help Responding to an 80G Approval Notice?
Received an 80G Approval Notice from the Income Tax Department and unsure about the next steps? A timely and properly prepared response can help ensure that your application is reviewed with complete information. At Ebizfiling, our experts can assist you in understanding the notice requirements, preparing the necessary response, and organising the supporting documents for your submission.
Get professional assistance for 80G(5) registration, Form 10AB compliance, and Income Tax notice responses with Ebizfiling.
Conclusion
Receiving an 80G Approval Notice does not automatically mean that the application has been rejected. It provides an opportunity for the organisation to submit additional details, documents, or clarifications required by the Income Tax Department. A timely and properly prepared response allows the authority to examine the application based on complete information. However, approval under Section 80G is granted only after verification of eligibility and compliance requirements.
Organisations should carefully review the notice, prepare a point-wise reply, and submit the required documents within the prescribed timeline to avoid delays in the approval process. Ebizfiling provides assistance with 80G registration, 12AB registration, and related Income Tax compliance requirements to help organisations manage their statutory obligations.
Frequently Asked Questions
1. What details are generally verified by the Income Tax Department before granting approval under Section 80G?
Before granting approval under Section 80G, the Income Tax Department may verify details such as the organisation’s registration status, objects of the institution, genuineness of activities, compliance history, financial records, and documents submitted with the application. The approval is granted after examination of the eligibility conditions prescribed under the Income-tax Act.
2. Can an 80G Approval Notice be issued after filing Form 10AB due to mismatch in submitted details?
Yes, an 80G Approval Notice may be issued if the details submitted in Form 10AB do not match with supporting records. Common mismatches may include differences in registration details, activity information, financial figures, trust objectives, or previous approval details. The applicant may need to provide clarification and supporting evidence.
3. What is the role of Form 10AC and Form 10AD in the 80G approval process?
Form 10AC is an order granting provisional or registration approval issued by the Principal Commissioner or Commissioner of Income Tax (Exemptions) after approval of the application. Form 10AD is issued in cases relating to approval under Section 80G or registration where applicable after examination of the application. The applicable order depends on the nature of approval granted.
4. What happens if the applicant fails to respond to an 80G Approval Notice issued under Section 80G proceedings?
If the applicant does not submit the required response within the prescribed timeline, the Income Tax Authority may decide the application based on available records. The authority may dispose of the application if the required information is not provided for verification.
5. Can the Income Tax Department provide a final opportunity before rejecting an 80G approval application?
Yes, in certain cases, the Income Tax Department may provide a final opportunity to submit pending details or documents before passing an order. The applicant should submit a complete response within the timeline mentioned in the notice or hearing communication.
6. What documents are examined by the Income Tax Department for verifying charitable activities under Section 80G?
For verification of charitable activities, the department may examine documents such as activity reports, details of beneficiaries, financial statements, utilisation of funds, donation records, bank statements, and evidence supporting the activities carried out by the organisation.
7. Can an 80G approval application be rejected due to non-compliance with 12AB registration requirements?
Yes, compliance with applicable registration requirements, including 12AB registration where applicable, may be examined while processing 80G approval. Any discrepancy in registration status, validity, or supporting documents may require clarification from the applicant.
8. What is the difference between rejection of Form 10AB application and disposal of an 80G approval application due to non-response?
Rejection generally refers to a decision taken after examination of the application where eligibility requirements are not satisfied. Disposal due to non-response may occur when the applicant fails to provide required information or documents, preventing proper examination of the application.
9. How should an organisation prepare a point-wise reply to an 80G Approval Notice? (Ebizfiling FAQ)
A reply to an 80G Approval Notice should address each query raised by the Income Tax Department separately, mention the relevant facts, attach supporting documents, and provide explanations wherever required. Ebizfiling assists organisations in reviewing notice requirements and preparing structured compliance responses.
10. Can Ebizfiling assist with Form 10AB compliance and 80G Approval Notice response? (Ebizfiling FAQ)
Yes, Ebizfiling can assist organisations with reviewing 80G Approval Notices, understanding departmental queries, organising required documents, and preparing responses related to Form 10AB and charitable compliance requirements.

Get Expert Support for 80G(5) Registration
Get professional support for 80G(5) Registration Online and understand the essential approval and compliance requirements for your charitable organisation.
About Ebizfiling -
October 6, 2026 By Srishti M
October 7, 2026 By Srishti M
October 3, 2026 By Srishti M
Revised ITR Under Old Tax Regime: Change Rules Explained Overview A salaried taxpayer may file an Income Tax Return under the new tax regime and later realise that the old tax regime could be more suitable because of eligible deductions […]