
ITR Filed Without Form 10IEA: 143(1) Notice Guide
Introduction
Many taxpayers filing an Income Tax Return under the old tax regime may receive a Section 143(1) intimation if Form 10IEA was required but not furnished within the prescribed timeline.
An ITR Filed Without Form 10IEA may create a difference between the tax regime selected by the taxpayer and the regime considered during return processing. This may impact the tax computation and result in adjustments, changes in tax liability or additional tax payable, depending on the facts of the case.
Taxpayers having income from business or profession who wish to opt out of the new tax regime and continue with the old tax regime are required to furnish Form 10IEA within the applicable timeline, wherever applicable.
For taxpayers who need assistance with correct return filing and tax compliance, they can also review Ebizfiling’s Income Tax Return Filing Service.
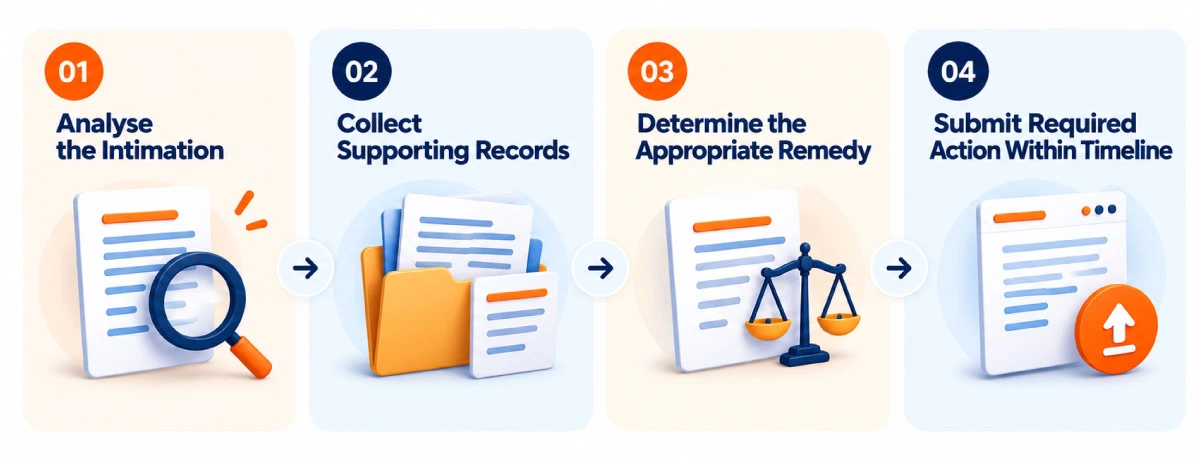
This article explains why an ITR Filed Without Form 10IEA may result in a Section 143(1) intimation, how taxpayers can identify the issue and what possible steps may be considered based on their specific circumstances.
Quick Insights
- Form 10IEA is required in specified cases where taxpayers with business or professional income want to opt out of the new tax regime.
- An ITR filed without Form 10IEA may create a mismatch between the intended tax regime and the regime considered during processing.
- Section 143(1) intimation communicates the outcome of return processing.
- Taxpayers should review the adjustment reason mentioned in the intimation before deciding further action.
- The available remedy depends on facts, timelines and applicable provisions.
- Completing tax regime-related compliance on time can help avoid processing-related differences.
What Happens When ITR is Filed Without Form 10IEA?
The new tax regime under Section 115BAC is the default tax regime. However, certain taxpayers having income from business or profession who wish to opt out of the new tax regime and choose the old tax regime are required to submit Form 10IEA within the prescribed timeline.
When an ITR Filed Without Form 10IEA occurs in such applicable cases, the following situation may arise:
- The taxpayer calculates tax liability considering the old tax regime.
- The required Form 10IEA declaration is not available for verification.
- The tax regime considered during processing may differ from the taxpayer’s intended selection.
- The final tax computation may vary from the calculation prepared while filing the return.
This difference may result in a Section 143(1) intimation showing additional tax payable or other adjustments.
Taxpayers should also understand that selecting a tax regime in the return and completing the required compliance for opting out of the default regime are separate aspects that must be properly completed.
November 4, 2026 By Srishti M
October 31, 2026 By Srishti M
October 29, 2026 By Srishti M