
-
October 12, 2026
Company Compliance Calendar November 2026: Key Due Dates & Filings
Introduction
The Company Compliance Calendar November 2026 highlights important annual return, dematerialisation and income tax compliances that companies may need to complete during the month.
November 2026 is particularly relevant for companies tracking MGT-7 / MGT-7A annual return filing, PAS-6 reconciliation requirements and ITR-6 filing for applicable companies, including those covered by transfer pricing provisions. Each compliance has separate applicability conditions, filing requirements and supporting documentation.
Reviewing these obligations in advance helps companies reconcile statutory records, avoid additional filing fees and interest, and complete their ROC and income tax compliances within the prescribed timelines.
In Brief
- The Company Compliance Calendar November 2026 covers key ROC, dematerialisation and income tax requirements applicable to companies.
- MGT-7 / MGT-7A annual return filing may apply based on the company category and relevant AGM timeline.
- PAS-6 applies only to companies covered by the prescribed dematerialisation requirements under Rule 9A or Rule 9B.
- ITR-6 filing timelines differ depending on whether section 92E transfer pricing provisions apply to the company.
- Companies should reconcile annual return data, share capital records and tax information before completing the applicable filings.
Important Due Dates in Company Compliance Calendar November 2026
|
Due Date |
Compliance |
Form |
Period |
Applicable To |
|
21/11/2026 |
Income Tax Return Filing – Extended Due Date | ITR-6 | AY 2026-27 |
Companies to whom section 92E does not apply |
|
29/11/2026 |
Annual Return Filing | MGT-7 / MGT-7A | FY 2025-26 |
Companies whose AGM was held, or should have been held, on 30 September 2026 |
|
29/11/2026 |
Reconciliation of Share Capital Audit Report | PAS-6 | Half-year ended 30 September 2026 |
Companies covered by Rule 9A / Rule 9B dematerialisation requirements |
|
30/11/2026 |
Income Tax Return Filing – Transfer Pricing Cases | ITR-6 | AY 2026-27 |
Companies to whom section 92E applies |
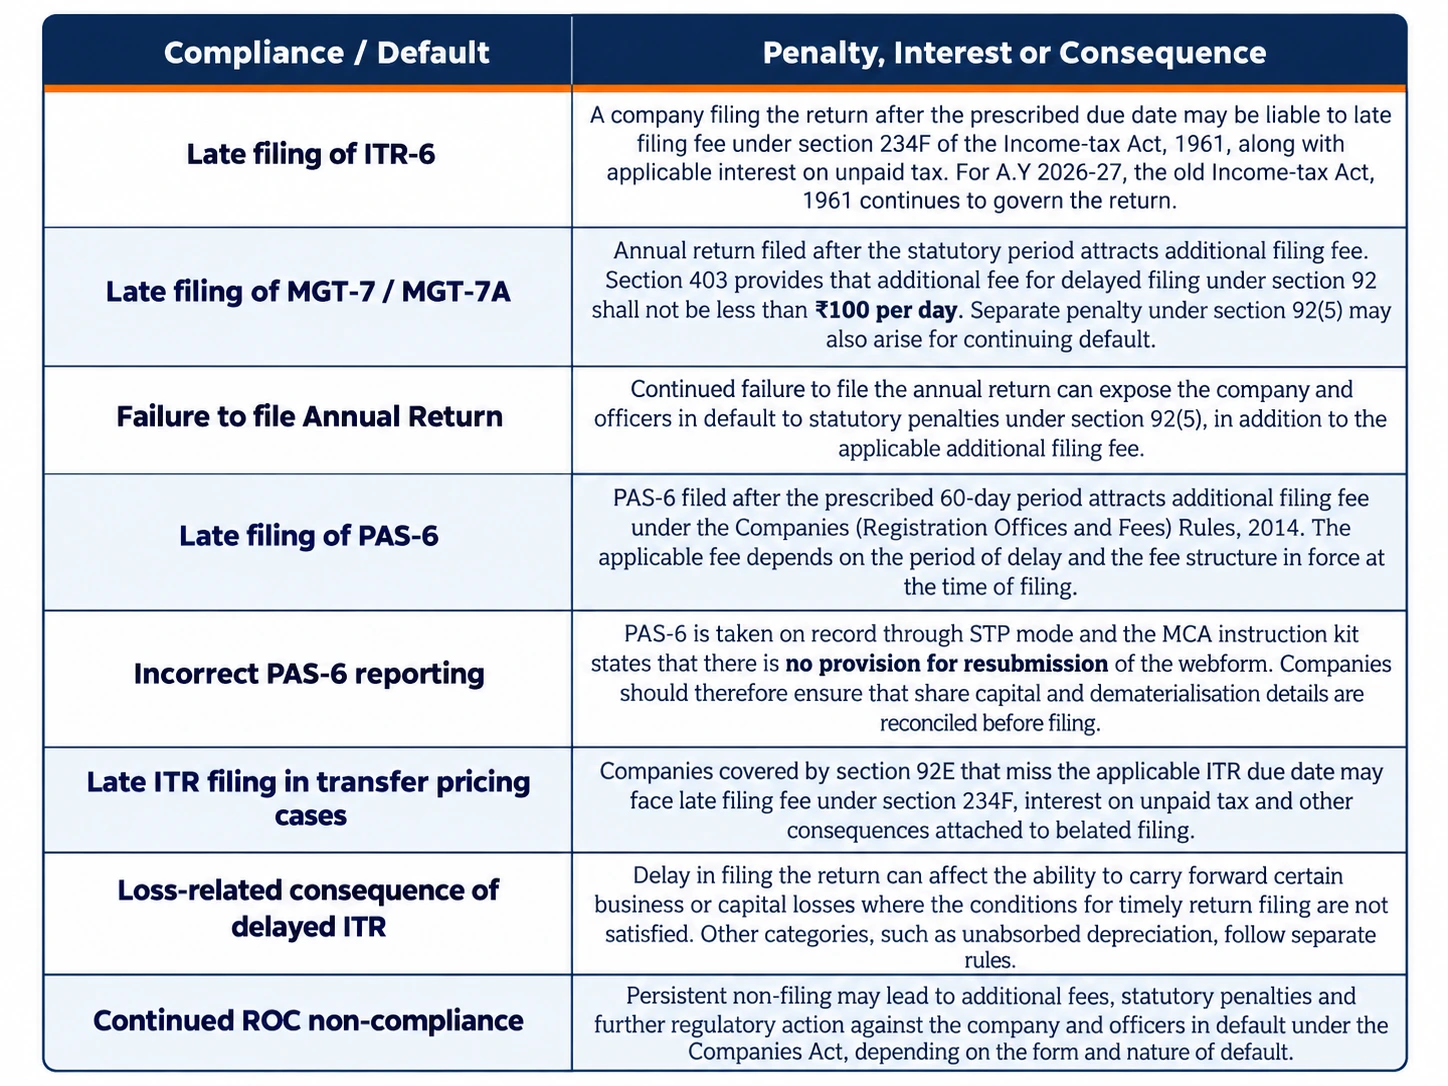
Penalty, Interest and Consequences of Non-compliance
Get Expert Assistance with November 2026 Company Compliance
ROC Filing Due? Let Ebizfiling Help You Stay Compliant!
Missed annual filings can lead to additional fees, statutory penalties and compliance difficulties.
At Ebizfiling, we help companies manage their applicable ROC and income tax filing requirements, including:
- MGT-7 / MGT-7A Filing: Annual return preparation and ROC filing assistance.
- PAS-6 Compliance: Share capital reconciliation and applicable filing support.
- ITR-6 Filing: Income tax return preparation and filing assistance.
- ROC Compliance Review: Verification of statutory records, pending filings and applicable deadlines.
For free consultation call us on 09643203209 or email info@ebizfiling.com
Conclusion
The Company Compliance Calendar November 2026 brings together important obligations relating to annual return filing, share capital reconciliation and income tax return filing for applicable companies.
Businesses should review AGM-related records, annual return information, dematerialisation applicability, share capital data and tax reporting requirements before completing the relevant filings. Proper reconciliation and timely submission can help maintain accurate MCA and tax records while reducing the risk of non-compliance.
For a wider view of statutory obligations during the month, refer to our Compliance Calendar November 2026, covering Company, LLP, GST, Income Tax, TDS and TCS, PF and ESI compliances.
Suggested Reads:
Compliance Calendar FY 2026-27
Compliance Calendar October 2026
GST Compliance Calendar November 2026
TDS and TCS Compliance Calendar November 2026
Frequently Asked Questions
1. Is MGT-7 filing required when a company fails to hold its AGM?
Yes. Under Section 92(4) of the Companies Act, 2013, the company must file its annual return within 60 days from the date on which the AGM should have been held, even if the AGM was not conducted. A statement explaining the reasons for not holding the AGM must also be submitted.
2. Can an OPC follow the same annual return deadline as other private companies?
An OPC follows a different compliance framework because it is exempt from holding an AGM. Its annual return in Form MGT-7A must generally be filed within 60 days after six months from the financial year-end. For FY 2025-26, this results in a filing deadline of 29 November 2026.
3. Is PAS-6 mandatory for a private company that has no securities in demat form?
Yes, if the private company is covered by Rule 9B and is required to comply with the dematerialisation provisions. The absence of dematerialised securities does not automatically remove the PAS-6 requirement. Applicability depends on the company’s classification, exemptions and prescribed compliance timelines.
4. What happens if a company's ISIN details do not match its paid-up capital records?
The company should reconcile its ISIN-wise security details, register of members, allotment records and depository statements before filing PAS-6. Any difference between issued capital and securities recorded with depositories should be investigated and appropriately reported. Unresolved discrepancies may create inaccurate statutory records and regulatory compliance concerns.
5. Is Form MGT-8 certification required along with MGT-7?
Yes, for listed companies and companies having paid-up share capital of ₹10 crore or more or turnover of ₹50 crore or more. Under Section 92(2) and Rule 11(2), their annual return must be certified by a practising Company Secretary in Form MGT-8. Companies below these thresholds generally do not require MGT-8 certification.
6. Does a company with international transactions automatically qualify for the 30 November ITR-6 deadline?
Not automatically. The company must determine whether its international transactions fall within the transfer pricing provisions requiring reporting under Section 92E of the Income-tax Act, 1961. Where Section 92E applies, Form 3CEB reporting is required, and the applicable ITR-6 filing deadline for AY 2026-27 is 30 November 2026, unless extended.
7. What happens if a company discovers an error after filing an annual ROC form?
The company should first check whether the form permits correction, resubmission or another MCA filing route. The correction method depends on the type of form, nature of error and whether the form has already been approved or taken on record.
8. How should a company handle transfer pricing applicability when filing ITR-6?
The company should review whether it has entered into international or specified domestic transactions covered by the transfer pricing provisions. If section 92E applies, the company must follow the separate reporting and ITR filing requirements applicable to transfer pricing cases.
9. Can Ebizfiling help review whether MGT-7, MGT-7A or PAS-6 applies to a company?
Yes. Ebizfiling can review the company’s classification, AGM records, share capital structure and dematerialisation applicability to help identify the correct ROC form and supporting requirements before filing.
10. How can Ebizfiling help when company records and MCA data do not match?
Ebizfiling can assist with reviewing MCA master data, statutory registers, annual return information, share capital records and supporting documents, and help identify the appropriate filing or correction process based on the mismatch.

Stay Ahead of Company Compliance Deadlines
Manage your company’s November 2026 filing deadlines with professional support for statutory filings, regulatory requirements, and ongoing compliance.
About Ebizfiling -
October 10, 2026 By Srishti M
October 10, 2026 By Srishti M
Compliance Calendar November 2026: Key Statutory Due Dates Introduction The compliance calendar November 2026 covers important statutory obligations under GST, Income Tax, TDS/TCS, Company Law, LLP regulations, EPF and ESI. It helps businesses identify the filings, payments and regulatory requirements […]
October 9, 2026 By Srishti M
80G Approval Notice : How to Respond and Avoid Rejection Introduction Charitable trusts, societies, and other eligible institutions may receive an 80G Approval Notice from the Income Tax Department while their application for approval under Section 80G is being processed. […]